REMAX COLLECTIVE • Pinellas COUNTY
REMAX Realtor in Largo, FL
The REMAX Collective Largo office sits in the Largo Professional Center on Seminole Boulevard — Pinellas County’s geographic center and the third-largest city in the county. From here, Barrett Henry and The NOW Team serve the beaches, barrier islands, and mainland communities of the Pinellas peninsula. If you’re buying or selling anywhere from Clearwater Beach to St. Pete, this is your REMAX office.
Barrett Henry, Broker Associate • FL License #BK3313308 • 23+ years of real estate experience
THE SHORT ANSWER
Barrett Henry is a licensed Florida Broker Associate at the REMAX Collective office at 11200 Seminole Blvd in Largo, serving Largo and all of Pinellas County. In this market three things decide most deals: whether your address sits in the City of Largo or unincorporated Pinellas, how much you can legally spend repairing a flood-zone home before the county forces you to elevate it, and whether a condo building has funded its structural reserves. Call (813) 733-7907 with an address and you will get a straight read on where each of those stands and who has to sign off on it.
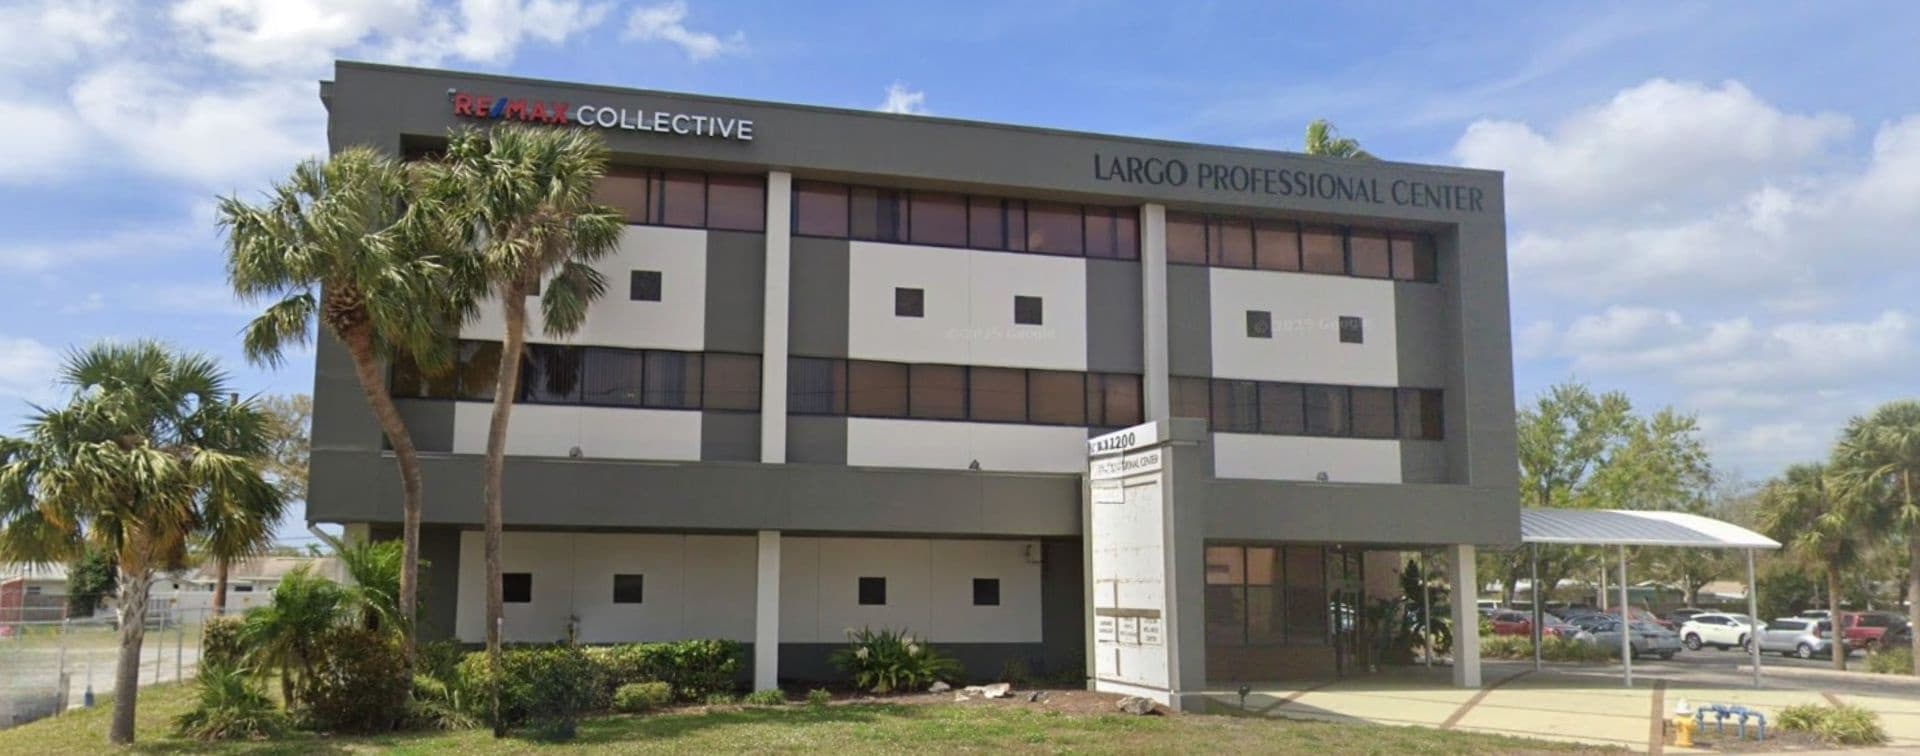
REMAX Collective Largo, 11200 Seminole Blvd, Ste 202, Largo, FL 33778
Your REMAX Largo Agent
Barrett Henry, Broker Associate
Barrett Henry is a licensed Florida Real Estate Broker Associate with REMAX Collective. With 23+ years of real estate experience, Barrett brings deep market knowledge, strong negotiation skills, and a no-nonsense approach to every transaction. Barrett is a REMAX Hall of Fame member and holds the e-PRO, MRP (Military Relocation Professional), and SRS (Seller Representative Specialist) designations.
Every client gets Barrett's direct cell phone number. No call centers. No runaround. No being handed off to a junior agent. Whether you're buying your first home, selling a property, investing in rental income, or relocating to Largo, Barrett and The NOW Team deliver results.
Office: 11200 Seminole Blvd, Ste 202, Largo, FL 33778
Direct: (813) 733-7907
Email: barrett@nowtb.com
License: FL Broker #BK3313308
Designations: e-PRO, MRP, SRS
Career Award: REMAX Hall of Fame
THE WORLD'S MOST RECOGNIZED REAL ESTATE BRAND
Why REMAX Largo?
When you work with Barrett Henry at REMAX Largo, you get more than a local agent. You get the full power of the most recognized real estate brand on the planet, a network that spans 120+ countries, 145,000+ agents, and over 50 years of proven results.
120+
Countries & Territories
145K+
Agents Worldwide
8,500+
Offices Globally
50+
Years in Business
The REMAX Advantage
REMAX was founded in 1973 by Dave and Gail Liniger in Denver, Colorado, on a simple idea: attract the best agents by letting them keep more of what they earn. That model attracted top producers from day one, and it still does. REMAX agents aren't beginners learning on your dime, they're experienced professionals who chose REMAX because they're serious about their careers.
The numbers prove it. REMAX agents averaged 11.7 transaction sides in 2025, versus 5.4 for agents at competing large brokerages more than double. That is not marketing spin: it is 18 consecutive years of independently verified data, drawn from the 2026 RealTrends Verified brokerage rankings covering U.S. brokerages that closed 500 or more sides.
American shoppers voted REMAX the most trusted real estate agency brand in the BrandSpark American Trust Study, published with Newsweek as the Most Trusted Awards, forfour years (2022 to 2025), plus 2019. The 2025 study surveyed 29,420 U.S. participants. REMAX also leads on 32.9% unaided brand awareness, meaning more people name REMAX first, without prompting, than any other real estate company (MMR Strategy Group study of unaided awareness, 2025 data). Your listing gets noticed.
Why REMAX Largo Specifically
- •Pinellas County is the most densely populated county in Florida — every transaction here requires local expertise that out-of-area agents simply don’t have
- •Located mid-county on Seminole Blvd with fast access to Clearwater, Indian Rocks Beach, Seminole, Belleair, and St. Petersburg
- •Beach and waterfront properties require specialized knowledge of flood zones, insurance, and coastal regulations — Barrett handles these daily
- •Pinellas is land-constrained on three sides, so new supply is limited, but the current market still favors prepared buyers, and pricing a listing correctly matters more here than almost anywhere in Tampa Bay
Areas We Serve from Largo
Clearwater • Clearwater Beach • Indian Rocks Beach • Belleair • Seminole • St. Petersburg • Treasure Island • Madeira Beach • Redington Beach • Dunedin • Safety Harbor • Palm Harbor
ABOVE THE CROWD SINCE 1978
The Most Recognized Logo in Real Estate
The REMAX hot air balloon first appeared at the 1978 Albuquerque International Balloon Fiesta and became the company's official logo shortly after. The balloon represents what REMAX agents do every day: rise above the crowd. It's not just a logo, it's the most recognized symbol in real estate worldwide.
Roughly 8 out of 10 U.S. homebuyers and sellers know of REMAX, and REMAX operates the largest hot air balloon fleet in the world about 106 balloons. No other real estate company comes close to that kind of global visibility.
When your home is listed with a REMAX agent, buyers recognize the brand immediately. That recognition translates to trust, and trust translates to more showings, stronger offers, and faster sales. In Largo, that brand power works for you from the moment the sign goes in the yard.
8 in 10
U.S. homebuyers and sellers know of REMAX, MMR Strategy Group
32.9%
unaided brand awareness, more people name REMAX first than any competitor
#1
Most trusted real estate agency brand, BrandSpark American Trust Study, 2022 to 2025
106
hot air balloons worldwide, the largest balloon fleet on earth
PROVEN RESULTS, NOT PROMISES
REMAX Agents Outperform the Competition 2-to-1
For 18 consecutive years, REMAX agents have sold more real estate per agent than agents at competing national brands. These aren't REMAX's numbers, they come from the independently compiled RealTrends Verified brokerage rankings.
| Metric | REMAX Agent | Industry Avg |
|---|---|---|
| Transaction sides per agent (2025) | 11.7 | 5.4 |
| Sales volume per agent (2025) | $5.3M | $3.2M |
| Unaided brand awareness | 32.9% | Varies |
| Countries / territories | 120+ | Varies |
Sources: transaction sides and sales volume per agent from the 2026 RealTrends Verified brokerage rankings (2025 data, U.S. brokerages closing 500+ sides / $350M+). Unaided brand awareness from MMR Strategy Group. Country count from REMAX Holdings, as of December 31, 2025.
Why do REMAX agents outproduce everyone else? Because the REMAX model attracts top talent. REMAX agents pay their own way, they cover desk fees and overhead rather than splitting commissions with the brokerage. That structure attracts driven, experienced professionals who don't need hand-holding. They choose REMAX because they want the brand, the tools, and the referral network, not because they need a broker to find them business.
That's the agent you want in your corner. In Largo, Barrett Henry embodies that REMAX standard: 23+ years of real estate experience, a REMAX Hall of Fame member, and a track record of getting deals done in every market condition.
145,000+ AGENTS IN 120+ COUNTRIES
The REMAX Referral Network
Moving to Largo from out of state? Relocating from Largo to another city, or another country? REMAX operates the largest agent-to-agent referral network in the real estate industry. With 145,000+ agents in 120+ countries, Barrett can connect you with a vetted, experienced REMAX agent at your destination, or receive a referral from an agent who's sending their client your way.
The REMAX referral platform, MAXRefer, launched in 2025 and is AI-powered. It matches agents based on location, specialties, production history, and client needs. It's not a random assignment, it's a data-driven match designed to pair your needs with the right agent. Separately, REMAX's global listing site publishes properties in 50 languages and 72 currencies, which matters when your buyer is overseas.
Pinellas County attracts international buyers — particularly from Canada, the UK, and Germany — drawn to the beaches and the lifestyle. REMAX’s presence in 120+ countries means Barrett connects directly with referring agents worldwide, making cross-border transactions seamless for buyers relocating to the Pinellas coast.
How REMAX Referrals Work
You Tell Barrett Where You're Going
Moving to Denver? London? Across town? Barrett identifies the right agent for your destination.
Barrett Connects You Directly
Through MAXRefer, Barrett matches you with a vetted REMAX agent who specializes in your destination market.
You're Taken Care Of, Anywhere
Your referred agent knows you came from Barrett. You get VIP treatment because your agent's reputation is on the line.
LOCAL MARKET EXPERTISE
The Largo Real Estate Market
Pinellas County is unlike any other market in Tampa Bay. Bounded by water on three sides, land is finite, so the long-term supply picture stays tight even when prices soften in the short term. The mix of gulf-front condos, historic bungalows in St. Pete’s arts district, and family homes in Seminole and Largo creates one of the most diverse real estate markets in Florida. Right now that market is split: single-family values have held roughly flat while older condos have repriced sharply as Florida’s new structural reserve requirements take hold. Knowing which side of that divide a property sits on is most of the job.
Barrett Henry doesn't just list homes in Largo, he knows the inventory, the comps, the school zones, the flood maps, the HOA restrictions, and the price trends block by block. That's the difference between a REMAX Broker Associate with 23+ years of real estate experience and an agent who just got their license last year.
BEFORE YOU BUY OR SELL HERE
What Largo Buyers and Sellers Need to Know
Pinellas County has rules that do not apply in most of the country. These are the ones that change what a property is worth, what you can do with it, and what it costs to own. Skip them and you find out the expensive way, usually after the inspection period has already closed.
What the Largo market is actually doing right now
Largo is a buyer-friendlier market than most of Pinellas County. Over the three months ending August 2026, the median Largo home sold for $349,669, down 3.9% year over year, while the Pinellas County median was $411,124, up 5.4%. That puts Largo roughly 15% below the county median one of the better value propositions on the peninsula.
Homes also move faster here. Largo’s median days on market was 50 days versus 75 days countywide. But sellers are negotiating: the median sale came in at 96.2% of list price, only 12.9% of homes sold above list, and 42.9% of homes on the market carried a price drop. Redfin scores Largo 45 out of 100 on competitiveness, “somewhat competitive,” not a frenzy.
Read that together and the strategy is obvious. Buyers have real negotiating room and should not be bullied into waiving inspections. Sellers who price to the current comps typically sell in roughly seven weeks; sellers who price to 2022 end up among the 43% carrying a price cut anyway, just later and from a weaker position.
Bottom line: Largo is priced about 15% under the county and sells 25 days faster. Buyers have leverage, and sellers who price right the first time do measurably better than those who chase the market down.
Are you in the City of Largo or unincorporated Pinellas? It changes the rules
This is the single most misunderstood thing about buying in Largo, and it costs people real money. A “Largo, FL” mailing address does not mean the property is inside Largo city limits. The Largo ZIPs, 33770, 33771, 33773, 33774, and 33778 cover both incorporated City of Largo parcels and large pockets of unincorporated Pinellas County. They also cross municipal lines: in closed sales over the past year roughly 15% of 33770 carried a Belleair Bluffs designation and about 20% of 33778 came through as Seminole. And despite what you will read elsewhere, 33777 is not a Largo ZIP 99% of its recent sales are designated Seminole. Which one you are in determines who issues your permits and which floodplain rule you live under.
The thresholds are genuinely different. The City of Largo treats a home as substantially damaged when repair costs reach 50% or more of the building’s market value. Unincorporated Pinellas County sets that line at 49% or more. Pinellas County states it plainly on its own site: if you live within a city, you have to contact that city for its substantial damage rules, the county’s do not apply to you.
There is a second, bigger consequence, and it shows up on your flood insurance bill every year. FEMA’s Community Rating System gives NFIP premium discounts based on how aggressively a community manages its floodplain, and each municipality is its own NFIP community with its own rating. Per FEMA’s eligible-communities list effective April 1, 2026, unincorporated Pinellas County is rated Class 2, earning a 40% flood insurance discount, while the City of Largo is Class 6, earning 20%. Two otherwise identical Largo-addressed homes can carry materially different flood premiums for no reason other than which side of the city line they sit on.
Do not generalize that to the rest of the county, either. Clearwater, Dunedin, and St. Petersburg are Class 5 at 25%; Belleair and Belleair Bluffs are Class 7 at 15%; Kenneth City and South Pasadena are Class 8 at 10%. And the City of Seminole does not appear on FEMA’s CRS eligible-communities list at all, which means no CRS discount there. Never assume a Pinellas municipality has a discount, and never apply the county’s number to a city parcel.
One percentage point sounds trivial until you are deciding whether a $180,000 renovation triggers a mandatory elevation. Before you write an offer on anything in a flood zone, confirm the jurisdiction on the Pinellas County Property Appraiser parcel record, then call that jurisdiction’s building department, Largo’s Building Division is (727) 586-7488, and Pinellas County Floodplain Management is (727) 464-7700.
Bottom line: Confirm the jurisdiction before you make an offer. City of Largo uses a 50% repair threshold and earns a 20% CRS flood discount; unincorporated Pinellas uses 49% and earns 40%. Same mailing address, different rules and different premiums.
How the 50% rule can cap your renovation before you start
The rule most people call the “FEMA 50% rule” works like this: if the cost to repair or improve a flood-zone building reaches the threshold for your jurisdiction, you can no longer simply repair it. The whole structure has to be brought into compliance with current floodplain code. The standard differs by jurisdiction: Pinellas County requires new and substantially improved buildings to be built at least one foot above base flood elevation, while the City of Largo requires the structure to be rebuilt or elevated to meet or exceed base flood elevation. Confirm the applicable standard with whichever department issues your permit.
Two details decide whether you clear the bar. First, market value means the building only, excluding the land and excluding site improvements like pools, fences, and landscaping. On a Largo lot where much of the price is the dirt, the structure value can be far lower than buyers assume, which makes the 49% or 50% ceiling far lower too. Second, costs are calculated at average commercial rates for labor and materials. Doing the work yourself or sourcing your own materials does not help; you still have to estimate it at market rates.
If you exceed the threshold, your options narrow to four: elevate and repair the existing home, replace it with an elevated home, relocate the home outside the flood hazard area, or remove it. None of those are cheap surprises to discover mid-project.
The leverage point is the valuation. Both jurisdictions let you establish the structure’s value with an independent appraisal of actual cash value rather than accepting the Property Appraiser’s adjusted just value, and Pinellas County offers a free pre-storm building value reconsideration through the Property Appraiser’s office. A higher documented structure value means a higher dollar ceiling before the rule bites. If you disagree with a determination, both Largo and the county have a reassessment process; Largo asks for photos, an elevation certificate, a detailed repair estimate, and an independent appraisal.
One more thing people learn the hard way: pull the permits. Largo is explicit that unpermitted work has to be removed or redone. Unpermitted repairs on a flood-zone property are one of the most expensive problems to inherit, and they surface at exactly the wrong moment, when you try to sell.
Bottom line: Your renovation ceiling is a percentage of the structure value, not the purchase price. Get that number established early, in writing, before you budget a flood-zone remodel.
Check the flood zone before you write the offer, not after
Much of Largo sits inland on the Pinellas peninsula, which generally means better elevation and lower flood risk than the barrier islands to the west. But “generally” is doing real work in that sentence. Across its roughly 18.8 square miles, Largo ranges from about 3 feet above sea level at its lowest to roughly 70 feet at its highest. That is a wide spread for a city this size, and it is precisely why flood zone designations here change street by street, sometimes within the same subdivision. Two houses a few blocks apart can carry completely different insurance obligations.
Pinellas County puts it bluntly on its own flood information page: everyone lives in a flood zone it may be high, moderate, or low risk, but “not in a flood zone” is not a thing here. The question is never whether you are in one, it is which one.
Flood zone drives your insurance cost, your lender’s requirements, whether you need an elevation certificate, and whether the substantial improvement rule above ever applies to you. It is a ten-minute check that changes the math on the entire purchase.
We already published the full breakdown rather than repeat it here: see Pinellas County Flood Zones: What Every Buyer and Homeowner Needs to Know for the zone types, how to look up a specific address, what an elevation certificate is, Risk Rating 2.0, and Florida’s flood disclosure requirements. For Largo waterfront specifically, see Waterfront Homes in Largo: Pricing & Flood Zones.
Practical checklist when you tour a Largo home: ask the seller for the current flood premium and declarations page, the elevation certificate if one exists, and the permit history. Ask your agent to check whether the seller’s flood policy can transfer to you, on some policies it can, and inheriting an older rate is worth real money. Then ask a Florida insurance agent to quote it for you, in your name, before your inspection period ends.
Bottom line: Inland Largo is lower-risk than the beaches, but zones vary block by block. Pull the zone, the elevation certificate, and a real insurance quote during due diligence.
The inspections and roof rules that decide whether you can insure it
In Florida the deal-killer usually is not the inspection report, it is the insurance underwriting that follows it. Worth knowing up front: Florida law does not require a four-point inspection. It is an insurance company underwriting requirement, and each carrier sets its own trigger. Citizens, for example, requires one for properties more than 20 years old. The four points are the roof, electrical, plumbing, and HVAC. Per the Florida Office of the Insurance Consumer Advocate, the report generally must be dated within 30 days before you submit the application not the 90 days to a year you will see repeated online, though each carrier sets the acceptable window. Budget roughly $100 to $300 and about an hour; a 20-minute inspection is a red flag, not a bargain.
Roof age is where Largo deals actually die. Citizens requires documentation showing at least five years of remaining useful life for roofs older than 25 years (shingle and similar) or 50 years (tile, slate, clay, concrete, metal). If the roof has less than five years left, the owner has to prove a full roof replacement before any policy will be written. Translation: on an older Largo home, find out the roof’s age and condition before your inspection period closes, because the answer can determine whether the property is insurable at all, and therefore whether it is financeable.
Now the part most buyers never hear, and it is in your favor. Under Florida Statute 627.7011(5), an insurer may not refuse to issue or renew a homeowner’s policy on a residential structure with a roof less than 15 years old solely because of the age of the roof. For a roof 15 years or older, you can get an inspection, and if it shows five or more years of useful life remaining, the insurer again may not refuse solely because of roof age. Roof age is measured from the last date 100% of the roof surface was built or replaced. The inspection has to be done by an authorized inspector the insurer recognizes, the statutory list includes licensed home inspectors, certified building code inspectors, professional engineers, architects, and general, building, or residential contractors, and since July 2024 explicitly roofing contractors. If a carrier is pushing back purely on roof age, that statute is worth quoting.
Two more rules worth knowing before you sign anything. Roof deductibles are capped. Under Statute 627.701(10), a separate roof deductible may not exceed the lesser of 2% of your Coverage A limit or 50% of the cost to replace the roof it is a ceiling set at whichever is lower, not a choice. It cannot be applied at all to a total loss under the valued policy law, to hurricane roof losses, to roof damage from a tree fall or similar hazard that punctures the roof deck, or to repairs requiring less than 50% roof replacement. And if your policy carries one, the premium must include an actuarially sound credit or discount for it.
Claim deadlines are short and they run from the date of loss, not from when you noticed. Under Statute 627.70132, notice of a new or reopened property claim must be given within one year of the date of loss, and a supplemental claim within 18 months. That applies to damage from any peril, not just hurricanes. If you are buying a Largo home that took storm damage, ask when the loss occurred and whether claims were filed and closed, those windows may already have expired, which means the repair is now the owner’s problem, and after closing, yours.
A rule that saves sellers real money: under Florida Statute 553.844(5), if an existing roof was built, repaired, or replaced in compliance with the 2007 Florida Building Code or later, and 25% or more of it is being repaired, replaced, or recovered, only the repaired or replaced portion has to meet the current code. This is statewide law, not a local Pinellas rule, and it is frequently misquoted as requiring a full tear-off.
Pinellas also has its own re-roof process. Every re-roofing project requires an in-progress inspection so the county can review the underlayment and roofing material during installation, and metal and tile roofs need separate dry-in and flashing inspections. Re-roofing mitigation affidavits are still required for concealed work like deck nailing. If you are buying a Largo home with a recent roof, confirm the permit was finaled, an uninspected re-roof becomes your problem at resale.
On the wind side, the Pinellas County Construction Licensing Board has adopted a 145 mph ultimate design wind speed (Vult) for Risk Category II buildings, which covers typical single-family homes, countywide across both incorporated and unincorporated Pinellas. That is the engineering standard new and substantially improved construction is designed against here. Pinellas sits outside Florida’s High-Velocity Hurricane Zone, which covers Miami-Dade and Broward, but is still fully subject to Florida’s hurricane wind-design requirements, a distinction that occasionally gets misread as “Pinellas has lighter standards.” It does not.
And file the wind mitigation form. The state form, OIR-B1-1802, was revised effective April 1, 2026, and the form itself states it is valid for up to five years provided no material changes to the structure. It documents nine items including roof covering, roof deck attachment, roof-to-wall attachment, roof geometry, secondary water resistance, and opening protection. Florida law requires residential property insurers to offer actuarially reasonable discounts for these features, so an uninspected home with hurricane-rated windows and a strapped roof is simply overpaying.
Bottom line: Check roof age before your inspection period closes, under 5 years of remaining life can make an older Largo home uninsurable until it is replaced. Then get a current wind mitigation inspection on the April 2026 form.
If your policy is with Citizens, two things are about to matter
Citizens Property Insurance is Florida’s insurer of last resort, and Pinellas leans on it heavily, as of June 30, 2026 Pinellas was Citizens’ fourth-largest county by exposure, with 21,401 policies and about $7.6 billion in insured value, behind only Miami-Dade, Broward, and Palm Beach. Statewide, Citizens is shrinking fast: 266,231 policies in force as of August 31, 2026, down from a peak of roughly 1.42 million in October 2023.
First deadline. Citizens has been phasing in a requirement that its policyholders carry flood insurance, by dwelling value: $600,000 and up in 2024, $500,000 and up in 2025, $400,000 and up in 2026, and all personal residential policies with wind coverage effective January 1, 2027. Citizens does not sell flood insurance, so you have to source it yourself, and your flood limit generally has to match your Citizens dwelling coverage or the maximum NFIP limit. Citizens lists condo unit-owner policies, tenant contents policies, and policies that exclude wind as not subject to the requirement. If you own a Largo home insured by Citizens and you do not carry flood today, that is a 2027 budget item you should price now, not in December.
Second: depopulation. Private carriers can make offers to assume your Citizens policy, and the rules are stricter than most owners realize. If an offer comes in no more than 20% above your estimated Citizens renewal premium, you are no longer eligible to stay with Citizens. If you do not register a choice by the deadline on the offer form, Citizens assigns you to the carrier with the lowest estimated premium. And once an assumption happens, it is final there is no longer a window to return to Citizens. Read the depopulation packet the week it arrives; it is not junk mail.
The better news: Florida regulators approved Citizens’ first average personal-lines rate decrease since 2015, effective July 1, 2026 for new policies and at renewal for existing ones, averaging about 8.8% lower for homeowners multiperil and 5.5% lower for wind-only, with every personal-lines policyholder getting at least a 2% reduction.
Finally, wind mitigation pays. Across all Citizens personal residential wind policies as of June 30, 2026, about 80% carried a windstorm mitigation credit, and those credits cut the wind portion of premium by roughly 52% on average, about $2,507 a year. Credits attach to documented features: roof covering, roof-deck attachment, roof-to-wall connections, secondary water resistance, opening protection, and roof shape. If a Largo home you are buying has had a roof replaced or shutters added and nobody filed a current wind mitigation inspection, that is money sitting on the table. Citizens does not publish per-feature credit percentages, so get an actual quote rather than trusting a percentage you read somewhere.
Bottom line: Citizens policyholders need flood coverage by January 1, 2027, and a depopulation offer within 20% of your renewal premium removes your right to stay. Get a current wind mitigation inspection either way.
Why Largo condo values fell while houses held: milestone inspections and SIRS
The divergence in this market is dramatic and it is not random. Over the year ending August 2026, the Zillow Home Value Index for Largo single-family homes rose 0.7% while the index for Largo condos and co-ops fell 8.3%. The typical Largo condo is now valued at roughly 43% of the typical Largo single-family home. Florida’s post-Surfside structural safety laws are a large part of why.
Our own read of Stellar MLS closed sales confirms it independently. Across the trailing twelve months in Largo, excluding rentals and manufactured housing, single-family homes sold at a $410,000 median in 28 days while condominiums sold at a $175,000 median in 74 days. That is condos trading at about 43% of the single-family price and taking more than two and a half times as long to sell two unrelated data sources landing on the same ratio. Townhomes and villas sat in between, at $322,450 and $235,000 medians respectively.
Two separate requirements apply to condo and co-op buildings that are three habitable stories or more. The first is the milestone inspection under Florida Statute 553.899: a structural inspection by a licensed engineer or architect by December 31 of the year the building turns 30 years old, then every 10 years after. Local authorities may require it at 25 years where conditions warrant, proximity to salt water is named in the statute, which matters across coastal Pinellas. A Phase 1 visual inspection is the default; a Phase 2 inspection with testing is triggered only if Phase 1 finds substantial structural deterioration.
The second is the Structural Integrity Reserve Study (SIRS) under Statute 718.112(2)(g), required at least every 10 years and covering the roof, load-bearing structure, fireproofing and fire protection, plumbing, electrical, waterproofing and exterior painting, windows and exterior doors, plus any item over $25,000 that affects structural integrity. Associations in existence on or before July 1, 2022 were required to complete a SIRS by December 31, 2025. Critically, associations that must have a SIRS can no longer vote to waive or underfund reserves for those specific components, apart from a narrow exception for certain multicondominium associations using a division-approved alternative funding method. There is limited flexibility: with a majority vote of the total voting interests, an association may fund repairs through a loan or line of credit, and for a budget adopted on or before December 31, 2028 it may pause reserve contributions for up to two consecutive budget years to fund repairs the milestone inspection recommended, provided the milestone was completed within the previous two calendar years and a SIRS is performed before contributions resume.
Translated into plain terms: buildings that deferred maintenance for thirty years are now legally required to find out what it costs and start funding it. That shows up as higher monthly dues and special assessments, and the market has repriced older condos accordingly.
This is not a reason to avoid Largo condos, it is a reason to buy them with your eyes open, and there are genuine bargains among well-run buildings. Before you waive due diligence, request the completed milestone inspection report, the SIRS, the current reserve balances, the last 12 months of board meeting minutes, and any special assessment already voted or under discussion. A building that has done the work and funded the reserves is a safer buy than a cheaper one that has not, the cheap one is often cheap precisely because the assessment has not landed yet.
Bottom line: Largo condo prices fell 8.3% largely because structural reserve funding is now mandatory. Get the milestone report, the SIRS, and the reserve balances before you remove your inspection contingency.
Buying for a school? Pinellas zoning does not work the way you think
This is where out-of-area buyers get hurt worst, because Pinellas does not behave like most districts. It is a zoned district with a choice program layered on top your address maps to a grid, the grid maps to an attendance zone, and that zone is your default school. But buying the house is not the same as getting the seat.
Read the district’s own rule carefully, because it is the single most important thing on this page for a family: new students entering kindergarten, sixth, or ninth grade are assigned to their zoned school. Every other new student is assigned to their zoned school on a space-available basis. If space is not available, the student is assigned to another school in the transportation cluster. Pinellas County Schools also states plainly that using its school locator “does not enroll a student, reserve a seat, or guarantee placement at any school.”
So if you are moving to Largo with a child entering, say, fourth or tenth grade, buying inside a zone guarantees you nothing. Call Pinellas County Schools Student Assignment at (727) 588-6210 and ask whether there is space in that specific grade at that specific school for a new zoned student, before you write the offer, not after you close.
Second trap: Largo is not one school district unto itself. Different Largo addresses feed different schools. Largo addresses are served by Largo High, Pinellas Park High, and Seminole High depending on where you are; middle schools include Largo Middle, Seminole, Osceola, and Morgan Fitzgerald; and at least seven zoned elementaries carry a Largo address, Anona, Frontier, Fuguitt, Mildred Helms, Oakhurst, Ridgecrest, and Walsingham Oaks K-8. Never trust a listing that names a school. Run the address yourself on the district locator at asd.pcsb.org/PubInfo.
Third: zones change. The Pinellas County School Board has been working through attendance-boundary changes that include Mid-County, Largo’s area. Any zoning statement, including the ones above, is perishable. The locator shows both the current year and proposed changes for the following year, so check both.
On the choice side, Largo sits in the district’s Mid/Central application area. Magnet programs may be countywide or limited to a geographic application area, while all fundamental programs are open countywide, so a Largo family can apply to any of them. Programs physically in Largo include Mildred Helms Elementary (IB Primary Years), Ridgecrest Elementary (Center for Gifted Studies), Largo Middle (IB Middle Years), Morgan Fitzgerald Middle (Center for Gifted Studies), Largo High (International Baccalaureate, Automotive Academy, and ExCEL), and Pinellas Park High (Criminal Justice Academy and First Responders).
Two things about choice that agents routinely oversell. Proximity priority is weak. It applies only to kindergarten, sixth, and ninth grade, only to your first-choice program, only after military, feeder-pattern, sibling, professional-courtesy, and school-board-employee priorities are satisfied, and it is capped at no more than 20% of remaining seats for elementary and middle, 25% for ninth grade. Buying nearer a magnet is not a strategy. And choice usually means you drive. Magnet and career academies get “arterial” busing if you are outside roughly two miles, but stops can sit more than a mile and a half from home and may require crossing a multi-lane road. Fundamental elementary programs and Special Assignment Requests come with no transportation at all, and buses do not run on private roads or inside gated communities.
Finally, a rule that quietly costs people their kid’s season: if you move, you must notify the principal within five days of the change of residence, even if you believe you are still in the same zone. Failure to give timely notice can mean reassignment to the zoned school and loss of eligibility for athletics and other activities. Residency documents are signed under penalty of perjury, and the district does investigate address fraud.
Bottom line: Only kindergarten, sixth, and ninth graders are guaranteed their zoned school, every other grade is space-available. Call Student Assignment at (727) 588-6210 about your child’s specific grade before you write an offer.
What you will actually pay in property taxes
The City of Largo’s municipal millage is 5.5200, unchanged since FY2023. That is only the city’s slice. Of every property tax dollar a Largo owner pays, the City of Largo gets roughly 29 cents; about 33 cents goes to Pinellas County Schools, about 29 cents to Pinellas County, and about 9 cents to special districts.
For the 2025 tax year a City of Largo parcel carried 18.9872 total mills: the city’s 5.5200, the School Board’s 6.2930 (the single largest line on the bill), the countywide levy of 4.6136 combining the general fund and Health Department, EMS at 0.8050, the Transit District at 0.7300, and 1.0256 across other districts the Juvenile Welfare Board, the Southwest Florida Water Management District, and the Pinellas Planning Council. Note what is not on that list: Largo parcels do not pay the county’s 0.5000 Library Services levy, because the city funds library service itself. Unincorporated parcels pay that levy, and an MSTU, instead of city millage. For your exact rate, pull the parcel on the Pinellas County Property Appraiser site rather than trusting any round number you read online, including ours.
Two Florida rules matter more than the millage itself. Save Our Homes caps annual assessed-value increases on a homesteaded property, which is why a long-time neighbor can pay a fraction of what you will pay on an identical house. And portability lets you carry your accumulated homestead savings to your next Florida home, a benefit a surprising number of move-up and downsizing sellers never claim.
If you are moving within Florida, run your numbers before you list: see our Florida property tax portability guide and Florida homestead exemption guide. The one thing to never miss is the filing deadline with the county Property Appraiser, losing a year of exemption is an entirely self-inflicted and avoidable cost.
Bottom line: Largo’s city millage is 5.5200, but that is under a fifth of your bill. Budget from the actual parcel record, and claim portability if you are moving within Florida.
Not sure how any of this applies to your property?
Send Barrett the address. He will pull the flood zone, the assessed value, the permit history, and the comps, then tell you straight what it means for your plans, no obligation and no sales pitch.
Largo Property Taxes vs. Other Pinellas Cities
Where you buy inside Pinellas County changes your municipal tax rate meaningfully. These are the adopted municipal millage rates for fiscal year 2025 to 26, the city portion only. Largo sits in the middle of the pack, below St. Petersburg, Clearwater, and Pinellas Park.
| City | Municipal millage (FY 2025 to 26) | Relative to Largo |
|---|---|---|
| St. Petersburg | 6.4525 | 0.93 higher |
| Clearwater | 5.8850 | 0.37 higher |
| Pinellas Park | 5.6500 | 0.13 higher |
| Largo | 5.5200 | , |
| Dunedin | 4.1345 | 1.39 lower |
| Seminole | 2.4793 | 3.04 lower |
Municipal millage only. These figures exclude the Pinellas County countywide levy, the Pinellas County School Board levy, and special districts, the school board levy is typically the largest single line on a Florida tax bill. Unincorporated Pinellas parcels pay no municipal millage, but pay a county MSTU of about 2.0857 plus the 0.5000 Library Services levy instead, still less overall than an incorporated Largo parcel. Sources: Florida Department of Revenue, Property Tax Oversight, Table 1 (Pinellas County), FY 2025 to 26 as adopted; Pinellas County Tax Collector 2025 millage table.
NEIGHBORHOOD BY NEIGHBORHOOD
Where People Actually Buy in Largo
Largo is not one market. Build era, elevation, lot size, and whether a neighborhood carries HOA dues change the real cost of ownership block by block. Every figure below, median sale price, days on market, HOA dues, square footage, pool rate, comes from Stellar MLS closed sales in Largo over the trailing twelve months, with rental records and manufactured housing excluded. These are measured, not guessed, and they will shift as the market does.
One caveat that matters more here than almost anywhere: these are grouped by Largo mailing address, because that is how buyers search and how the MLS files them. A Largo mailing address does not always mean the parcel sits inside Largo city limits, several of the best-known names below are legally in unincorporated county. We flag those individually, because the distinction changes your permits, your floodplain rules, and your tax bill.
Pinebrook Estates
In the 33773 Largo mailing area, and the busiest single subdivision in our Largo sales data. Know this before you search: most of the broader Pinebrook plat falls inside the City of Pinellas Park, and only the northern section is City of Largo, confirm the jurisdiction on the specific parcel. The figures here reflect the Largo-addressed portion: 26 closed sales in the last 12 months, more than anywhere else in Largo, at a $394,500 median and 26 days on market. Early-1980s homes around 1,380 sq ft, typically 3 bed / 2 bath. About a third of sales carry an HOA, median dues near $380, and roughly a quarter have a private pool.
Largo Lake Villas
North Largo (33770) and the fastest-moving address in town: a 6-day median time to contract at $367,500. Despite the name these are detached single-family homes, built around 1963, compact at roughly 1,100 sq ft. Recent sales show no HOA, and about a quarter have a pool.
Keene Park
Northeast Largo (33771), just off Keene Road. Seven days to contract at a $345,000 median, second-fastest in Largo. Mid-1960s homes near 1,075 sq ft, usually 2 bed / 2 bath, and recent sales show no HOA dues.
Harbor Bluffs
A Largo mailing address that is NOT inside Largo city limits, county records place these parcels in unincorporated Pinellas near Belleair Bluffs, and 609 of the 680 parcels mail as Largo. That is exactly the trap this page warns about, so confirm jurisdiction before you budget permits. It is also the top of the conventional market: a $762,500 median that still moved in 25 days. The largest homes on this list at roughly 2,140 sq ft, late-1950s construction, 3 bed / 3 bath. Around 60% have a private pool and most sales carry modest HOA dues near $420. Note the Largo mailing address does not necessarily mean inside Largo city limits.
Del Prado Imperial
Southwest Largo (33774), toward the beaches. A $539,500 median in 20 days, with the biggest floor plans in the fast-moving tier at about 1,615 sq ft and frequently 4 bedrooms. Early-1970s construction, 40% with pools, and HOA dues that are nominal where they exist.
Orangewood Estates
South Largo (33778). A $485,000 median in just 8 days, which is unusual at that price point. Mid-1970s homes around 1,575 sq ft, 3 bed / 2 bath, no HOA on recent sales, and notably about 64% come with a private pool, the highest pool rate on this list.
Harbor Crest
Southwest Largo (33774), closer to the Gulf side. A $515,000 median in roughly 13 days. Late-1950s homes near 1,435 sq ft, 3 bed / 2 bath, no HOA on recent sales, and about 63% have pools.
Mill Pond
Southwest Largo (33774). A $400,000 median in 15 days, late-1970s homes around 1,330 sq ft, 3 bed / 2 bath. Recent sales show no HOA, and close to half include a pool.
Highland Park
North Largo (33770) and one of the oldest pockets in the city, median year built 1951. Eighteen sales at a $295,800 median in 21 days makes it Largo's most active entry-to-mid market. Roughly 1,165 sq ft, 3 bed / 2 bath, no HOA and essentially no pools on recent sales.
Sun Coast Estates
East Largo (33771). A $323,500 median in about 12 days. Late-1950s homes near 1,430 sq ft, often 3 to 4 bedrooms, no HOA on recent sales.
Floral Gardens
East Largo (33771). A $331,000 median in 27 days, mid-1970s homes around 1,335 sq ft, 3 bed / 2 bath, no HOA on recent sales and roughly a quarter with pools.
Roosevelt Groves
North Largo (33770) and confirmed inside Largo city limits, one of the larger platted subdivisions in the city at 335 homes. A $290,000 median at 40 days, early-1970s homes near 1,080 sq ft, 3 bed / 2 bath, no HOA on recent sales.
Big Acres
West Largo (33774) and confirmed inside city limits, 239 homes. A $375,000 median, though at 58 days it moves slower than the fast tier. Homes from around 1960 near 1,225 sq ft, 3 bed / 2 bath, no HOA on recent sales.
Marsandra Estates
West Largo (33770), confirmed inside city limits. A $384,000 median at 40 days across 9 sales. Late-1950s homes around 1,130 sq ft, and notably about 56% of recent sales included a private pool. No HOA on recent sales.
Lakeview of Largo
Southwest Largo (33774) and confirmed inside city limits, at 513 units, one of the largest condo communities in the city. A $147,300 median across 20 sales, but 61 days to contract, which is typical for Largo condos right now. Early-1970s construction.
Shadow Lakes
South Largo (33778), confirmed inside city limits, 151 condo units. A $151,500 median at 35 days across 11 sales, quicker than most Largo condo product. Early-1980s construction.
Orange Lake Village
South Largo (33773) and the city's entry-level volume leader, 23 sales in the original section at a $255,000 median, plus a second section that moved in 13 days at $272,000. Mid-1950s homes, genuinely small at roughly 815 to 870 sq ft and often 2 bed / 1 bath. The most affordable site-built houses in Largo.
Lake Seminole Village
South Largo (33773). Attached villas from the mid-1980s, about 1,340 sq ft, that moved at a $284,950 median in 9 days. Every sale carries an HOA, median dues around $369 a month, budget that in alongside the price.
Belle Oak Villas
East Largo (33771). Mid-1980s villas near 1,035 sq ft, 2 bed / 2 bath, at a $250,000 median in 24 days across 15 sales. All sales carry an HOA with median dues around $264 a month. One of the more liquid low-maintenance options in Largo.
Azalea Shores
Southwest Largo (33774) and effectively the only new construction in the city, median year built 2025. Townhomes around 1,675 sq ft, 3 bed / 3 bath, at a $400,000 median with HOA dues near $165. Took about 40 days to contract, slower than resale single-family but the trade is a brand-new building envelope and a current-code roof.
Shipwatch
Southwest Largo (33774), gated and genuinely on the water, about half of recent sales were waterfront. The parcel sits in unincorporated Pinellas County despite the Largo mailing address. A $325,000 median, but two numbers matter more: 58 days on market and median HOA dues near $980 a month. That fee is the tradeoff for the location and the marina setting, and it is the kind of condo carrying cost to verify against the reserve study before you commit.
Imperial Point
Another Largo mailing address that is not City of Largo, county records put these 613 parcels in unincorporated Pinellas under Seminole jurisdiction, 454 of them mailing as Largo. Large 1970s homes averaging roughly 2,200 sq ft at a $580,500 median, with HOA dues near $700 a month and a 61-day median time to contract. Space and location at the cost of carrying expense and slower resale.
REMAX COMMERCIAL
Commercial Real Estate in Largo
REMAX Commercial has been part of the REMAX network since 1990. In 2023, REMAX Commercial practitioners closed more than $17.5 billion in volume across 60,000+ commercial transaction sides, through 11,000+ commercial brokers in 640+ offices. REMAX Commercial agents have access to institutional-grade tools including CoStar, LoopNet Premium, Crexi Professional, and Catylist the same platforms used by the largest commercial brokerages in the world.
Pinellas County’s commercial landscape includes Gulf Boulevard hospitality properties, US-19 retail corridors, downtown St. Pete office space, and the growing Clearwater industrial market. Through REMAX Commercial, Barrett assists investors and business owners with acquisitions, dispositions, and 1031 exchanges across the peninsula.
Commercial Property Types
Retail
Office
Multifamily
Industrial
Land
Special Use
EDUCATION & CREDENTIALS
REMAX Agents Are the Most Trained in the Industry
REMAX University offers 60+ relevant designations, certifications, and courses plus over 2,000 on-demand videos. In a REMAX study of 3,000 U.S. agents recruited between January 2021 and March 2024, new agents who engaged with REMAX University closed 60% more transactions and earned145% more in commissions from their first year to their second. Barrett Henry holds multiple industry designations that directly benefit his clients.
e-PRO
Certified in digital marketing, social media strategy, and technology-driven real estate. Barrett leverages online tools to market your property to the widest possible audience.
MRP
Military Relocation Professional. Trained to serve active-duty military, veterans, and their families during PCS moves. Barrett understands VA loans, BAH, and military timelines.
SRS
Seller Representative Specialist. Advanced training in listing presentations, pricing strategy, and seller advocacy. Your interests come first, every step of the way.
REMAX Career Awards
REMAX recognizes top-producing agents through a tiered award system based on gross commission income. The club levels below are annual commission tiers; Hall of Fame and the awards above it are career totals. Thresholds are administered regionally, so exact figures can vary by region. Barrett Henry is a REMAX Hall of Fame member, an honor reserved for agents who have earned $1 million+ in gross commissions during their REMAX career. Here's how the award levels work:
Executive Club
$50K to $99K
100% Club
$100K to $249K
Platinum Club
$250K to $499K
Chairman’s Club
$500K to $749K
Titan Club
$750K to $999K
Diamond Club
$1M to $1.99M
Pinnacle Club
$2M+
Hall of Fame
$1M+ career
LUXURY REAL ESTATE
The REMAX Collection
The REMAX Collection is REMAX's luxury division, reserved for properties priced at two times or more the average sold price in the listing area. In Largo and the Tampa Bay market, that means waterfront estates, golf course properties, gated community homes, and high-rise condos that command premium pricing.
REMAX Collection listings receive elevated marketing: professional photography, dedicated luxury property websites, international exposure through REMAX's global network, and placement on luxury-specific portals that attract high-net-worth buyers. Barrett Henry brings the same attention to detail and negotiation skill to luxury transactions that he does to every deal.
Homes for Sale in Largo
Latest active listings near the REMAX Collective Largo office. Updated daily from Stellar MLS.
 Active
$385,000
3568 4TH AVENUE
LARGO, FL 33771
 Active
$514,998
11515 IMPERIAL GROVE DRIVE
LARGO, FL 33774
 Active
$349,999
1640 KAY DRIVE
LARGO, FL 33770
 Active
$499,000
616 HERITAGE LANE
LARGO, FL 33770
 Active
$770,000
4415 CLEARWATER HARBOR DRIVE
LARGO, FL 33770
 Active
$409,900
14036 THACHER AVENUE
LARGO, FL 33774
 Active
$399,000
2117 MARY SUE STREET
LARGO, FL 33774
 Active
$159,900
10493 PEACEFUL DRIVE
LARGO, FL 33773
 Active
$524,900
1231 ROSEWOOD STREET
LARGO, FL 33770
 Active
$364,900
14800 WALSINGHAM ROAD
LARGO, FL 33774
 Active
$399,000
14800 WALSINGHAM ROAD
LARGO, FL 33774
 Active
$175,000
12261 SAILWINDS DRIVE
LARGO, FL 33773
CLIENT REVIEWS
What Clients Say About Barrett at REMAX Largo
★★★★★
“Working with Barrett Henry has truly been THE BEST experience I've ever had with a realtor. From start to finish, he made the process smooth and stress-free.”
Regina Castillo
Tampa Bay
★★★★★
“We have used Barrett many times for both buying and selling properties, and he has always exceeded our expectations.”
Sandra Misuraca
Tampa Bay
★★★★★
“I've had Barrett as my realtor for 10 years now. After using his services to sell my first house, I never needed to find another agent.”
Ryan Mauk
Tampa Bay
3 TAMPA BAY LOCATIONS
REMAX Collective Offices
Barrett Henry serves all of Tampa Bay from three REMAX Collective office locations. No matter where your property is, Barrett is never more than a short drive away.
REMAX Collective Largo
11200 Seminole Blvd, Ste 202, Largo, FL 33778
You Are Here
REMAX Collective Tampa
14310 N. Dale Mabry Hwy, Ste 100, Tampa, FL 33618
View REMAX Tampa →
REMAX Collective Brandon
417 Lithia Pinecrest Rd, Brandon, FL 33511
View REMAX Brandon →
FREE LARGO RESOURCES
Keep Reading, Largo Guides
Every guide below was written for this market specifically. No gates, no email required. Read what you need and call when you want a second opinion on your own situation.
Buying in Largo
Selling in Largo
Frequently Asked Questions, REMAX Largo
What is the median home price in Largo, FL?
Over the three months ending August 2026 the median Largo home sold for $349,669, down 3.9% from a year earlier, according to Redfin. That is about 15% below the Pinellas County median of $411,124 for the same period, which makes Largo one of the better-value markets on the Pinellas peninsula. Median price per square foot was $245.
How long does it take to sell a house in Largo, FL?
The median Largo home went under contract in 50 days as of August 2026, compared with 75 days for Pinellas County overall, per Redfin. Expect negotiation: the median sale closed at 96.2% of list price, and 42.9% of Largo homes on the market carried a price drop. Pricing correctly at launch is typically the difference between about seven weeks and several months.
Am I in the City of Largo or unincorporated Pinellas County?
A Largo mailing address does not settle it, the Largo ZIPs (33770, 33771, 33773, 33774, and 33778) include both City of Largo parcels and large pockets of unincorporated Pinellas County. Those ZIPs also cross city lines: roughly 15% of recent 33770 sales were designated Belleair Bluffs and about 20% of 33778 came through as Seminole, and 33777, often listed as Largo, is actually 99% Seminole. It matters because the two have different floodplain repair thresholds: the City of Largo uses 50% of the building's market value, while unincorporated Pinellas County uses 49%. Check the parcel record on the Pinellas County Property Appraiser site, then call that jurisdiction's building department, Largo Building Division at (727) 586-7488 or Pinellas County Floodplain Management at (727) 464-7700.
What flood insurance discount does Largo get?
Per FEMA's Community Rating System eligible-communities list effective April 1, 2026, the City of Largo is rated Class 6, which earns a 20% NFIP flood insurance discount. Unincorporated Pinellas County is rated Class 2 and earns 40% double Largo's discount. Because every municipality is its own NFIP community, the discount follows the property's community, not the county, so an address inside Largo city limits and one just outside it can pay noticeably different flood premiums. For reference, Clearwater, Dunedin, and St. Petersburg are Class 5 at 25%, and the City of Seminole does not appear on the CRS list at all.
What is the FEMA 50% rule in Largo, FL?
If the cost to repair or improve a flood-zone building reaches 50% or more of the building's market value, excluding the land, the City of Largo treats it as substantially damaged, and the structure must be rebuilt or elevated to meet or exceed base flood elevation. Unincorporated Pinellas County applies the same concept at 49%, and requires new and substantially improved buildings to be built at least one foot above base flood elevation. Costs are calculated at average commercial labor and material rates even if you do the work yourself, and you can establish a higher structure value through an independent appraisal of actual cash value.
Does my Largo condo need a milestone inspection or a SIRS?
If the building is three habitable stories or more, yes to both. Florida Statute 553.899 requires a milestone structural inspection by December 31 of the year the building turns 30, then every 10 years, and local authorities may require it at 25 years where conditions such as proximity to salt water warrant it. Statute 718.112(2)(g) separately requires a Structural Integrity Reserve Study at least every 10 years, and associations that existed before July 1, 2022 were required to complete one by December 31, 2025. Request both reports plus current reserve balances before you waive your inspection contingency.
Why are Largo condo prices falling?
Largo condo and co-op values fell 8.3% in the year ending August 2026 while single-family values rose 0.7%, per the Zillow Home Value Index. The main driver is Florida's post-Surfside structural safety law: buildings three stories and up must now complete milestone inspections and fund a Structural Integrity Reserve Study, and associations subject to a SIRS can no longer vote to waive or underfund reserves for structural components. That means higher dues and special assessments, and the market has repriced older buildings to reflect it. Well-run buildings that have already completed the work and funded reserves are often the better buy.
What is the property tax rate in Largo, FL?
The City of Largo's municipal millage is 5.5200, unchanged since FY2023, and a City of Largo parcel carried 18.9872 total mills for the 2025 tax year. The city's share is roughly 29 cents of every property tax dollar; about 33 cents goes to Pinellas County Schools, 29 cents to Pinellas County, and 9 cents to special districts. The bill combines the city's 5.5200, the School Board's 6.2930, a countywide 4.6136, EMS at 0.8050, Transit District at 0.7300, and 1.0256 in other districts. Largo parcels do not pay the county's 0.5000 Library Services levy because the city funds library service itself. Pull your parcel on the Pinellas County Property Appraiser site for your exact rate.
Does buying a house in a Largo school zone guarantee my child a seat?
Only at three grades. Pinellas County Schools assigns new students entering kindergarten, sixth, or ninth grade to their zoned school, but all other new students are assigned to their zoned school on a space-available basis. If space is not available, the student is assigned to another school within the transportation cluster. The district also states that its school locator does not enroll a student, reserve a seat, or guarantee placement. If your child is entering any grade other than K, 6, or 9, call Student Assignment at (727) 588-6210 and ask about space in that specific grade and school before you write an offer.
Which schools serve Largo, FL?
Largo is not served by a single set of schools, it depends on the address. Largo addresses feed Largo High, Pinellas Park High, or Seminole High; middle schools include Largo Middle, Seminole, Osceola, and Morgan Fitzgerald; and at least seven zoned elementaries carry a Largo address: Anona, Frontier, Fuguitt, Mildred Helms, Oakhurst, Ridgecrest, and Walsingham Oaks K-8. Attendance boundaries also change, and the Pinellas County School Board has been reviewing Mid-County boundaries. Always run the specific address on the district locator at asd.pcsb.org/PubInfo rather than relying on a school named in a listing.
Will an old roof stop me from insuring a Largo home?
It can stop the purchase entirely. Citizens requires documentation showing at least five years of remaining useful life for roofs older than 25 years (shingle or similar) or 50 years (tile, slate, clay, concrete, or metal), and if the roof has less than five years left the owner must prove a full roof replacement before any policy will be written. No policy means no financing. Check the roof's age and condition before your inspection period closes, not after. Note also that Florida law does not require a four-point inspection at all, it is an insurance underwriting requirement, and Citizens triggers it on properties more than 20 years old.
Can a Florida insurer refuse to cover my Largo home because of the roof's age?
Not on roof age alone, within limits. Under Florida Statute 627.7011(5), an insurer may not refuse to issue or renew a homeowner's policy on a home with a roof less than 15 years old solely because of the roof's age. If the roof is 15 years or older, you may obtain an inspection, and if it shows five or more years of useful life remaining, the insurer again may not refuse solely because of roof age. Roof age runs from the last date 100% of the roof surface was built or replaced. The inspection must be performed by an authorized inspector the insurer recognizes, the statute lists home inspectors, building code inspectors, engineers, architects, general, building and residential contractors, and since July 2024, roofing contractors.
How long do I have to file a storm damage claim in Florida?
Under Florida Statute 627.70132, notice of a new or reopened property insurance claim must be given within one year of the date of loss, and a supplemental claim within 18 months of the date of loss. The clock runs from the date of loss, not from when you discovered the damage, and it applies to damage from any peril rather than just hurricanes. If you are buying a Largo home that sustained storm damage, ask when the loss occurred and whether a claim was filed and closed, if those windows have passed, the unrepaired damage becomes the buyer's problem after closing.
Does a roof repair in Largo mean replacing the whole roof?
Not necessarily. Under Florida Statute 553.844(5), if an existing roof was built, repaired, or replaced in compliance with the 2007 Florida Building Code or any later edition, and 25% or more of it is being repaired, replaced, or recovered, only the repaired or replaced portion must meet the current code. This is statewide Florida law, not a Pinellas rule, and it is widely misquoted as requiring a full tear-off. Separately, Pinellas County requires an in-progress inspection on every re-roofing project, so confirm any recent roof permit was properly finaled before you buy.
Does Citizens Property Insurance require flood insurance in Largo?
Yes, and the final phase lands soon. Citizens has been phasing in a flood insurance requirement by dwelling value, $600,000 and up in 2024, $500,000 and up in 2025, $400,000 and up in 2026, and all personal residential Citizens policies with wind coverage must carry flood insurance effective January 1, 2027. Citizens does not sell flood coverage, so you have to obtain it separately, and the limit generally must match your Citizens dwelling coverage or the maximum NFIP limit. Citizens lists condo unit-owner policies, tenant contents policies, and policies excluding wind as not subject to the requirement. Price it now rather than at renewal.
Is Largo, FL a good place to buy right now?
Largo currently favors prepared buyers. Prices are down 3.9% year over year, 42.9% of listings cut price before selling, only 12.9% sold above list, and Redfin scores the market 45 out of 100 on competitiveness. That is real negotiating room, and it means you should not be pressured into waiving inspections or flood due diligence. Largo also runs about 15% below the county median while sitting inland of the barrier islands, which generally means better elevation than the beach communities. Call Barrett Henry at (813) 733-7907 to talk through whether your specific situation fits this market.
Where is the REMAX office in Largo?
The REMAX Collective Largo office is at 11200 Seminole Blvd, Ste 202, Largo, FL 33778. Barrett Henry is a Broker Associate at this location. Call (813) 733-7907 to schedule an appointment or just walk in.
Why should I choose REMAX over other brokerages in Largo?
REMAX is the most recognized real estate brand in the world, operating in 120+ countries with 145,000+ agents. REMAX agents averaged 11.7 transaction sides in 2025 versus 5.4 for agents at competing large brokerages, more than double, per the 2026 RealTrends Verified rankings. When you list with REMAX, your property benefits from global brand recognition, the largest referral network in real estate, and an agent (Barrett Henry) with 23+ years of real estate experience.
Who is the best REMAX agent in Largo?
Barrett Henry is a top-producing Broker Associate and REMAX Hall of Fame member at REMAX Collective in Largo. With 23+ years of real estate experience, FL Broker License #BK3313308, and designations including e-PRO, MRP, and SRS, Barrett has the credentials and track record that matter.
Does REMAX Largo handle commercial real estate?
Yes. Through REMAX Commercial, Barrett handles commercial transactions including retail, office, multifamily, industrial, and land deals in Largo and the Tampa Bay area. REMAX Commercial agents have access to CoStar, LoopNet Premium, and Crexi Professional.
How does the REMAX referral network help me?
Moving to or from Largo? Barrett connects you with a vetted REMAX agent at your destination through MAXRefer, the AI-powered global referral platform REMAX launched in 2025, spanning a network present in 120+ countries and territories. You get a warm introduction to a trusted agent, not a random name from a search engine.
What is the REMAX balloon?
The REMAX hot air balloon is the most recognized logo in real estate. It debuted at the 1978 Albuquerque Balloon Fiesta and represents the REMAX motto: “Above the Crowd.” REMAX operates about 106 hot air balloons, the largest balloon fleet in the world. Roughly 8 out of 10 U.S. homebuyers and sellers know of REMAX.
How do I contact REMAX in Largo?
Call Barrett Henry directly at (813) 733-7907 or email barrett@nowtb.com. The Largo office is at 11200 Seminole Blvd, Ste 202, Largo, FL 33778.
Does REMAX Largo help with rentals and property management?
Yes. Barrett and The NOW Team assist with both sales and rentals across Largo and the Tampa Bay area. For full-service property management, visit vivipm.com (ViVi PM).
Sources & Where to Verify This Yourself
- City of Largo, Substantial Damage / FEMA 50% Rule
- City of Largo, Substantial Damage FAQs
- Pinellas County, Substantial Damage & Substantial Improvement Rule (49% threshold, unincorporated)
- Pinellas County, Construction in a Floodplain (one foot above base flood elevation)
- Florida Statute 553.899, Milestone inspections
- Florida Statute 718.112, Structural Integrity Reserve Study requirements
- Redfin, Largo, FL housing market (August 2026)
- Redfin, Pinellas County, FL housing market (August 2026)
- Zillow Research, Zillow Home Value Index data (August 2026)
- Florida Department of Revenue, Property Tax Oversight, millage by county and municipality
- City of Largo, How your property taxes fund city services
- Pinellas County Property Appraiser, parcel and millage lookup
- Pinellas County Tax Collector, property tax and millage rates by taxing district
- U.S. Census Bureau, Largo, Florida population and land area
- U.S. Geological Survey, elevation data (3DEP)
- Citizens Property Insurance, flood insurance requirement phase-in
- Citizens Property Insurance, depopulation / assumption process
- Citizens Property Insurance, 2026 approved rate decrease
- Citizens Property Insurance, policies in force and county exposure reports
- Citizens Property Insurance, windstorm mitigation discounts
- Citizens Property Insurance, inspection and roof requirements
- Florida Office of the Insurance Consumer Advocate, what to expect: four-point inspection
- Florida Statute 553.844, windstorm loss mitigation; roof repair 25% rule
- Florida Statute 627.0629, residential property insurance windstorm discounts
- Florida Statute 627.7011, roof age and refusal to insure
- Florida Statute 627.701, roof deductible limits
- Florida Statute 627.70132, property claim notice deadlines
- Florida OIR, wind mitigation form OIR-B1-1802 and resources
- Pinellas County Construction Licensing Board, local technical amendments (ultimate design wind speed)
- Pinellas County, roofing inspection policies
- Pinellas County, flood information and flood maps
- FEMA, Community Rating System eligible communities list (effective April 1, 2026)
- Pinellas County Schools, school zone locator
- Pinellas County Schools, new student registration and zoned school assignment
- Pinellas County Schools, magnet, fundamental and application programs
- Stellar MLS closed sales data, Largo, trailing 12 months (accessed via Bridge Interactive)
Market figures move month to month and the rules above get amended by the Florida Legislature and by local ordinance. Everything here was accurate when published, but verify anything you are relying on for a transaction, or call Barrett and he will confirm the current numbers for your specific property. Nothing on this page is legal, tax, or insurance advice.
Contact REMAX Largo
Reach Barrett Henry at the Largo office. Call (813) 733-7907 or send a message below.
Ready to Work with REMAX Largo?
Barrett Henry, Broker Associate • REMAX Hall of Fame • 23+ years of real estate experience