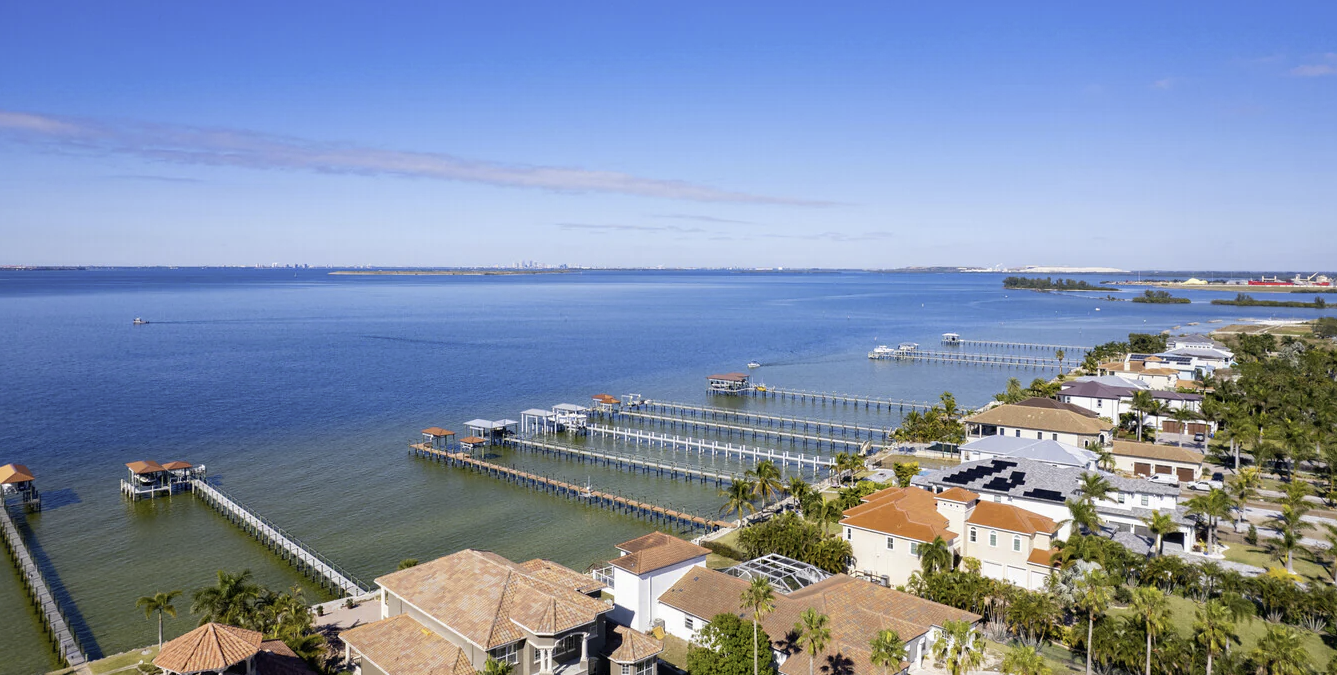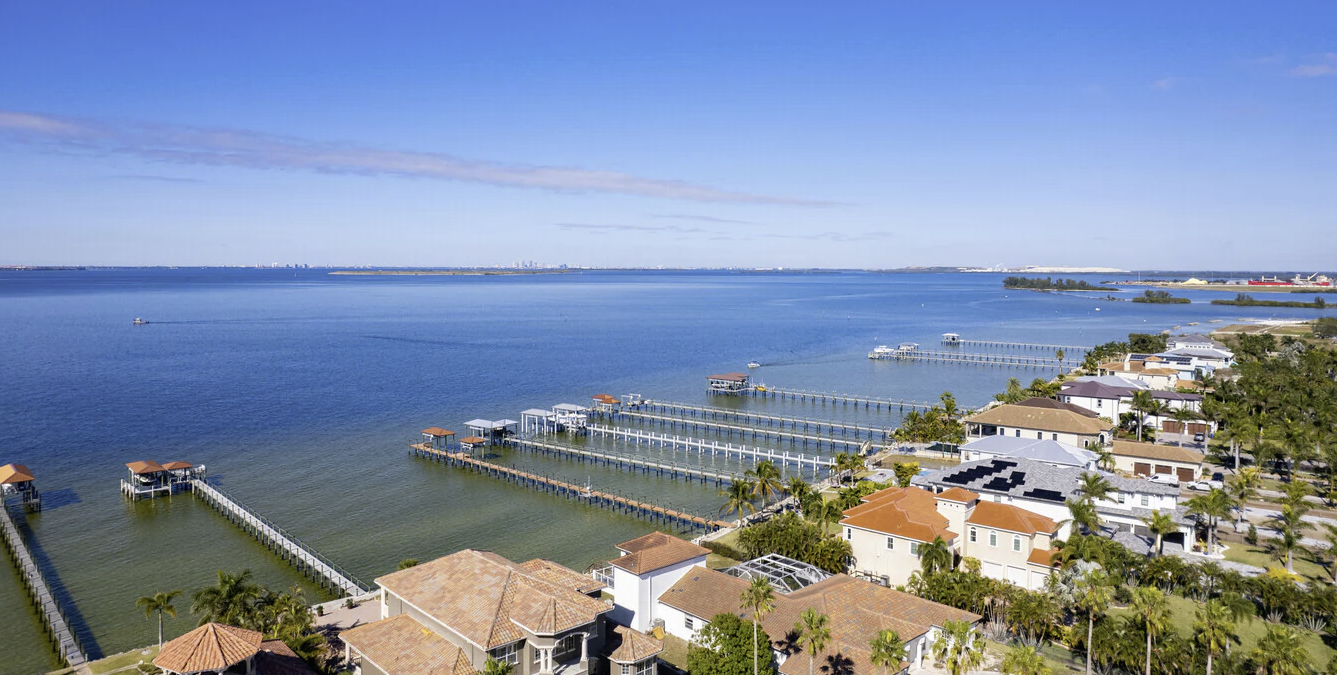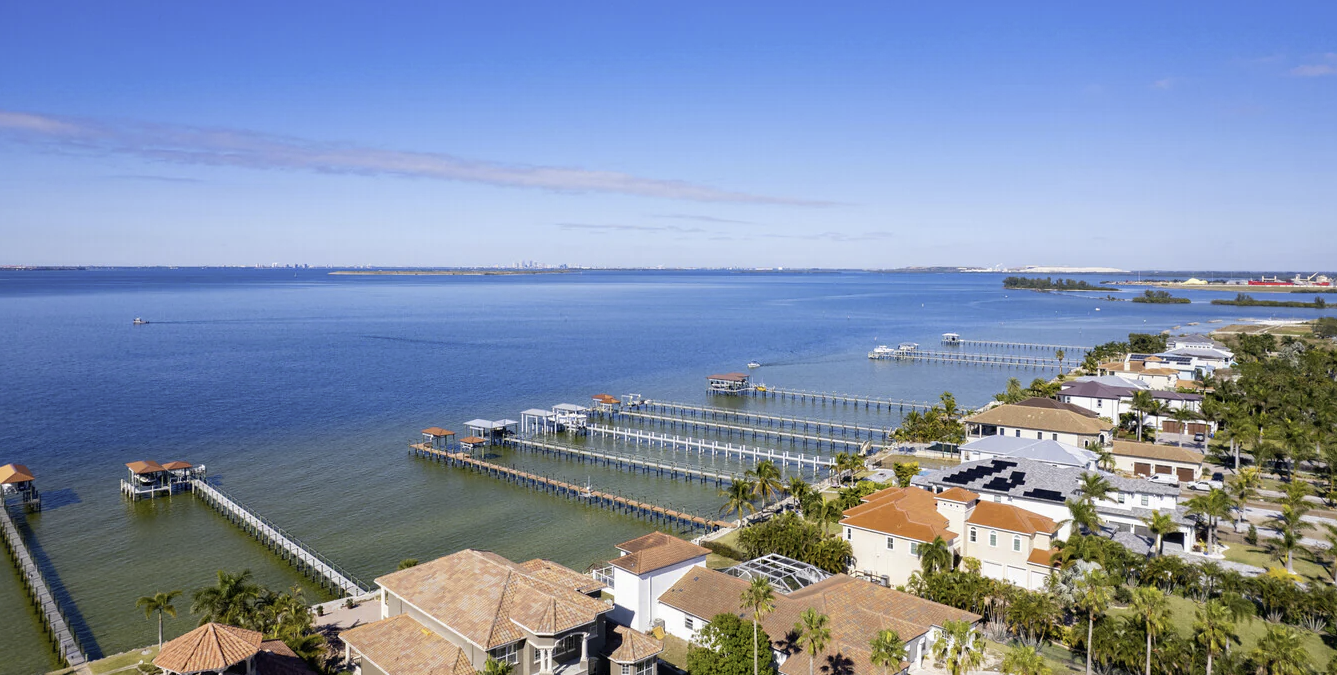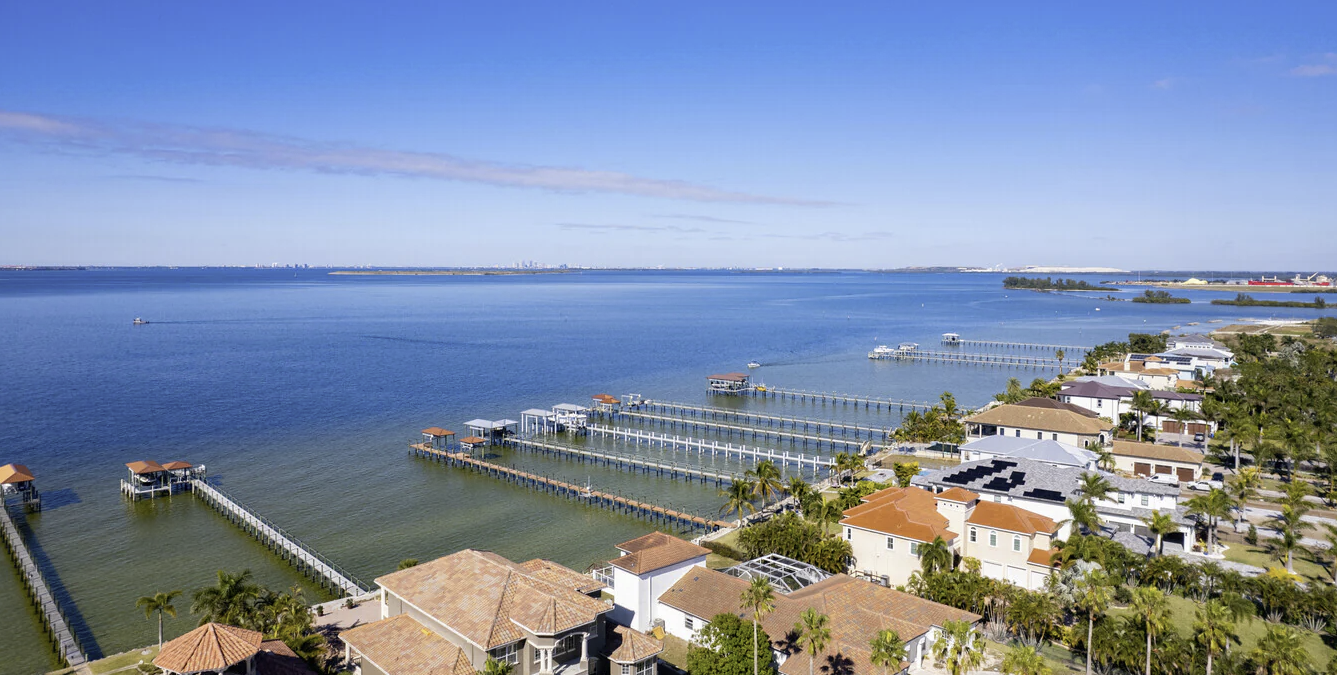
Apollo Beach is a waterfront community in southern Hillsborough County where most properties sit in FEMA-designated flood zones. Flood insurance is mandatory for homes with federally backed mortgages in Special Flood Hazard Areas (AE, AH, VE zones). Annual premiums through the National Flood Insurance Program (NFIP) range from $900 to $6,000+ depending on zone, elevation, and structure type. Private flood insurance is available and sometimes cheaper. Barrett Henry at REMAX Collective helps buyers understand flood costs before closing. Call (813) 733-7907.
Apollo Beach and Flood Risk: Why It Matters Before You Buy
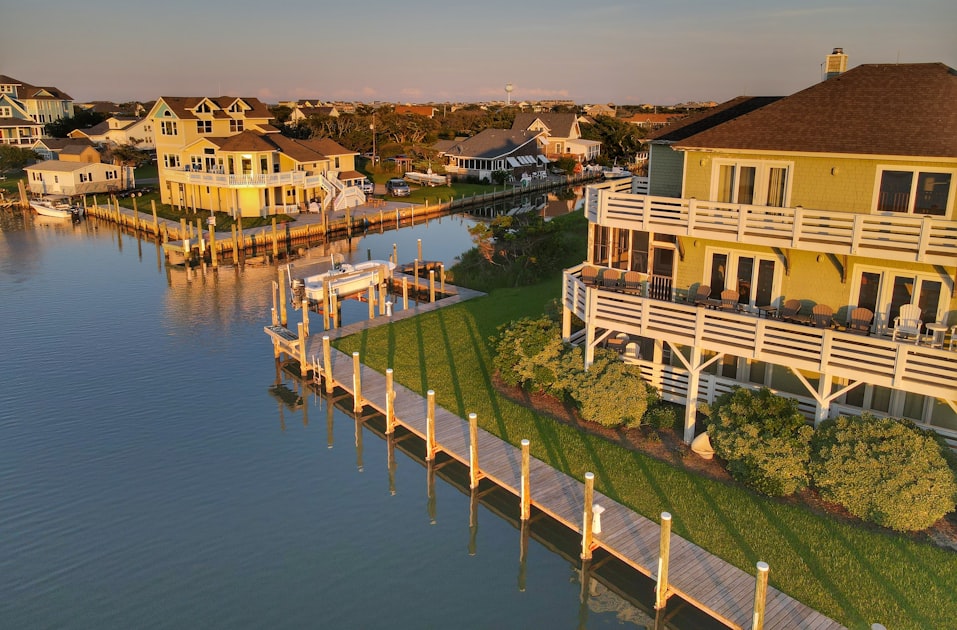
Apollo Beach was developed in the 1960s and 1970s by dredging channels and filling wetlands along Tampa Bay. The design created hundreds of lots with direct canal access and boat docks, making it one of the most boat-friendly communities in Hillsborough County. That same geography creates meaningful flood exposure that every buyer needs to understand before making an offer.
Flood insurance is not optional in many parts of Apollo Beach. If your lender is federally backed (which covers virtually all conventional, FHA, and VA loans), and your property sits in a FEMA Special Flood Hazard Area, flood insurance is required at closing and must be maintained for the life of the loan.
FEMA Flood Zones in Apollo Beach
| FEMA Zone | Description | Insurance Required? |
|---|---|---|
| AE | Special Flood Hazard Area, 1% annual chance flood, base flood elevation established | Yes (mandatory with federal loan) |
| AH | Special Flood Hazard Area with shallow flooding, ponding likely | Yes (mandatory with federal loan) |
| VE | Coastal high-hazard area with wave action | Yes (mandatory, highest risk category) |
| X (shaded) | Moderate flood hazard, 0.2% annual chance | Not required, strongly recommended |
| X (unshaded) | Minimal flood hazard, outside 500-year floodplain | Not required |
Most waterfront and canal-front properties in Apollo Beach fall in AE zones. Some properties in lower-elevation interior sections may also be in AE or AH zones. A meaningful number of Apollo Beach properties fall in Zone X, particularly those on higher ground in newer sections north of Big Bend Road.
How NFIP Flood Insurance Premiums Are Calculated
The National Flood Insurance Program (NFIP) uses Risk Rating 2.0, implemented in 2021, which calculates premiums based on the specific property's flood risk rather than just its zone designation. Key factors:
- Elevation relative to Base Flood Elevation (BFE): Homes built above BFE pay significantly less. Each foot above BFE can reduce premiums by 15-30%.
- First floor height: How high the lowest livable floor sits above grade
- Structure type: Single-family, condo, mobile, elevated vs. slab
- Coverage amount: NFIP caps at $250,000 for the structure and $100,000 for contents
- Distance to water: Properties closer to open water or flood sources pay more
- Building characteristics: Foundation type, number of floors, basement
Typical Apollo Beach Flood Insurance Costs
| Property Type | Typical Annual NFIP Range | Notes |
|---|---|---|
| AE zone, slab-on-grade, at BFE | $2,500-$5,000 | Common in older canal homes |
| AE zone, elevated 2+ ft above BFE | $900-$2,200 | Newer construction, elevated slabs |
| AE zone, 3+ story, ground floor garage | $1,200-$2,800 | Flood risk limited to garage level |
| Zone X (shaded), no NFIP required | $500-$1,200 | Voluntary coverage, lower risk |
| Private flood insurance, AE zone | $1,800-$4,500 | Can exceed NFIP $250K coverage cap |
These ranges reflect 2025-2026 market conditions. Individual rates vary based on the specific property's elevation certificate data.
Elevation Certificates and Why They Matter
An Elevation Certificate is a document prepared by a licensed surveyor or engineer that records the elevation of the lowest floor of a structure relative to the Base Flood Elevation. Elevation Certificates are used by insurance agents to calculate NFIP premiums.
If a home is in an AE zone, an Elevation Certificate can either confirm the premium is accurate or reveal that the home sits higher than the flood map suggests, potentially reducing the premium significantly. For older Apollo Beach homes where the original certificate may be outdated or missing, ordering a new one (typically $400-$700) can be one of the best investments a buyer makes before closing.
Ask the seller's agent if an Elevation Certificate exists for any Apollo Beach property in a Special Flood Hazard Area. If not, factor the cost of obtaining one into your negotiation or request the seller provide it.
Private Flood Insurance vs. NFIP
Since 2016, the private flood insurance market in Florida has grown substantially. Private carriers now offer policies that in some cases beat NFIP pricing and offer coverage above the NFIP's $250,000 structure cap.
Advantages of private flood insurance:
- Coverage limits above NFIP caps (up to $4M or more)
- Can include additional living expenses after a flood
- Sometimes lower premiums than NFIP for lower-risk properties
- No NFIP waiting period (NFIP has a 30-day waiting period before coverage takes effect)
Disadvantages:
- Private carriers can non-renew after a major hurricane season
- Coverage terms vary significantly by carrier
- Lender must accept the private policy (most do if it meets FEMA equivalency standards)
Get quotes from both NFIP and private market carriers before closing. An independent insurance agent familiar with Hillsborough County flood markets can run comparisons for you.
Flood History and Hurricane Exposure
Apollo Beach sustained significant flooding during Hurricane Helene in September 2024, when storm surge pushed saltwater into dozens of canal-front homes. That event was a reminder that Tampa Bay is vulnerable to major storm surge from Gulf storms approaching from the south or southwest.
When evaluating Apollo Beach properties, ask for:
- Seller's disclosure regarding prior flood claims (required under Florida law)
- NFIP claims history for the property (available through the agent via NFIP reporting)
- Evidence of any flood mitigation improvements (French drains, grading, elevated HVAC)
- Flood vent installations in foundation walls (required for enclosed lower areas in AE zones)
What Post-Hurricane Flood Disclosure Requires in Florida
Florida law (FS 689.302) requires sellers to disclose prior flooding if the property has flooded at least twice in the last five years, or if the seller has made an NFIP claim. Sellers must also disclose if the property is in a flood zone. Buyers should request the seller's property disclosure statement and review it carefully for any flood history.
Want New Listings Before the Crowd Sees Them?
Barrett can set up alerts so matching homes reach you the day they hit the market, which is often the difference between touring a house and reading about the sale.
Barrett Henry, REALTOR®
Licensed Florida Real Estate Broker, REMAX Collective
23+ years of real estate experience
No obligation, no pressure
Barrett Henry is a Broker Associate at REMAX Collective with 23+ years of real estate experience. He helps buyers and sellers in Apollo Beach navigate flood zone requirements, insurance costs, and the full due diligence process for waterfront properties. Call (813) 733-7907 or visit nowtb.com.
Frequently Asked Questions: Apollo Beach FL Flood Insurance
Is flood insurance required in Apollo Beach FL?
Flood insurance is required for properties with federally backed mortgages (conventional, FHA, VA) located in FEMA Special Flood Hazard Areas (AE, AH, VE zones). Most Apollo Beach canal-front and waterfront properties fall in these zones. For properties in Zone X, flood insurance is not required but is often recommended given Tampa Bay's hurricane exposure.
How much is flood insurance in Apollo Beach FL?
Annual flood insurance premiums in Apollo Beach typically range from $900 to $6,000+ depending on the FEMA zone, elevation certificate data, and coverage amount. Homes built at or above Base Flood Elevation pay significantly less than older slab-on-grade homes that sit below BFE. Get an elevation certificate to confirm your rate is accurate.
What is the difference between NFIP and private flood insurance?
NFIP is the federal program with a 30-day waiting period and coverage caps of $250,000 for structure and $100,000 for contents. Private flood insurance is offered by private carriers, sometimes at lower premiums, with higher coverage limits and no waiting period. Private carriers can non-renew after major storm seasons. Compare both options before closing on any Apollo Beach property.
Can I appeal my flood zone designation in Apollo Beach?
Yes. If you believe your property has been incorrectly mapped in a flood zone, you can apply for a Letter of Map Amendment (LOMA) or Letter of Map Revision (LOMR-F) through FEMA. A LOMA requires an elevation certificate showing the lowest ground adjacent to the structure is at or above the Base Flood Elevation. If approved, mandatory flood insurance is no longer required. This process takes 60-90 days and costs $700-$1,500 including surveyor fees.
Did Apollo Beach flood during Hurricane Helene in 2024?
Yes. Hurricane Helene caused significant storm surge flooding in Apollo Beach in September 2024. Canal-front properties experienced saltwater intrusion from Tampa Bay surge. Sellers are required to disclose prior flood damage under Florida law. When making an offer on any Apollo Beach property, ask for the seller's disclosure statement and check for NFIP claims history.
Should I buy in Apollo Beach given the flood risk?
That depends on your risk tolerance and what you are buying. Apollo Beach offers boating access, waterfront lifestyle, and canal-front properties that are genuinely difficult to find elsewhere in Hillsborough County at comparable price points. The flood risk is real and should be priced into your offer via insurance cost analysis and due diligence. Elevated properties with flood vents and proper mitigation carry meaningfully lower risk and lower insurance costs than older slab-on-grade canal homes.
Explore More Apollo Beach and Tampa Bay Resources
- Apollo Beach vs Riverview FL
- Sell Home Fast Gibsonton FL
- Thonotosassa FL Real Estate
- Brandon FL No HOA Homes
- Valrico FL Homes with Acreage
- Dover FL Homes with Acreage
- Lithia FL Horse Properties
- Seffner FL Homes Under $350K
- FishHawk Ranch HOA CDD Fees
- Is FishHawk Ranch Good to Live?
- Why Buyers Choose Brandon FL
- First Time Buyer Valrico FL
- Dover FL Property Taxes
- Cost of Living Plant City FL
- Sell Home Fast Anna Maria FL
- Sell Home Fast Bartow FL
- Sell Home Fast Holiday FL
- Sell Home Fast Dade City FL
- Plant City FL Things to Do
- FishHawk Ranch Community Guide
- Brandon No HOA Listings
- Lithia Horse Property Guide
Let's Find Your Next Home
Search live Tampa Bay listings, then call Barrett Henry to see the ones worth your time. 23+ years of real estate experience on your side of the table.