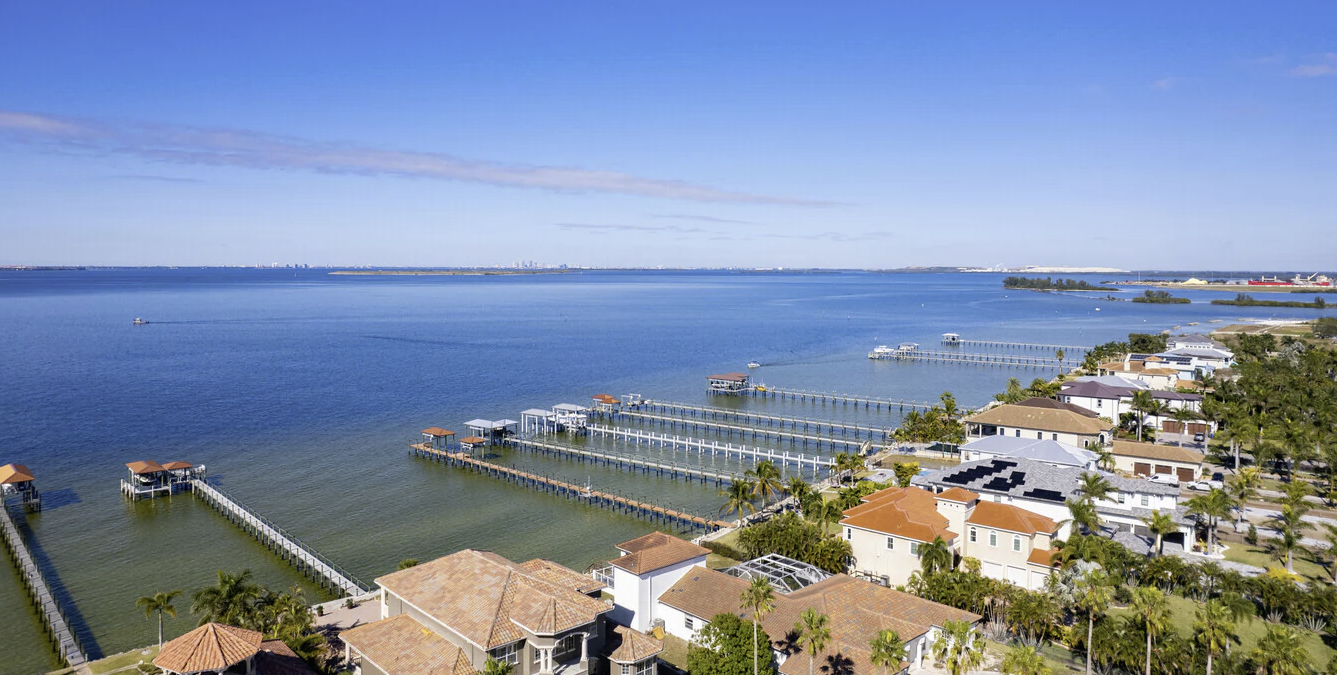
If you own a home in Apollo Beach and you're reading this, there's a good chance you went through something difficult in the fall of 2024. Hurricane Helene hit in late September, bringing significant storm surge and flooding to waterfront and canal-front properties across Apollo Beach. Less than two weeks later, Hurricane Milton followed with destructive winds and even more flooding. Back-to-back storms like that are brutal - not just physically, but emotionally and financially. I'm Barrett Henry with REMAX Collective, and I've been working with Apollo Beach homeowners through this exact situation since the storms hit. Some of you are dealing with insurance claims that are still open. Some have started repairs. Some are looking at a damaged home and wondering whether it makes more sense to fix it or sell it and move on. This guide is for all of you. I'm going to walk through your options honestly - what selling after hurricane damage looks like, what repairs cost versus what they return, what Florida law requires you to disclose, and how to make the decision that's right for your family and your finances.
Quick Decision Guide - Your Situation and Best Path Forward
| Your Situation | Best Option | Typical Timeline | Key Consideration |
|---|---|---|---|
| Minor cosmetic damage, insurance claim settled | Repair and sell at full market value | 2--4 months | Repairs are straightforward; you'll recover most or all of your investment |
| Significant structural damage, insurance claim open | Wait for claim resolution, then decide | 4--8 months | Selling with an open claim complicates the transaction significantly |
| Major damage, no flood insurance | Sell as-is to cash buyer/investor | 2--6 weeks | You'll sell below market but avoid repair costs you can't finance |
| Moderate damage, insurance covers most repairs | Repair and sell at market value | 3--6 months | Repaired homes sell for significantly more than as-is properties |
| Damage repaired, but you want to leave Apollo Beach | List at full market value with a local agent | 30--90 days | A fully repaired, properly documented home sells close to pre-storm value |
| Emotional attachment, damage is manageable | Repair and stay | Varies | If you love the location and can afford the repairs, staying is valid |
| Mold discovered after flooding | Remediate immediately, then decide | 2--8 weeks for remediation | Mold gets worse and more expensive every week you wait |
How Helene and Milton Affected Apollo Beach
I want to be specific about what happened here because the damage in Apollo Beach was different from what other Tampa Bay communities experienced. Apollo Beach sits on Tampa Bay with an extensive canal system running through the community. That's what makes it special for waterfront living - and it's also what made it especially vulnerable during these storms.
Hurricane Helene (September 26, 2024)
Helene made landfall in the Big Bend region of Florida, but the storm surge it pushed into Tampa Bay was devastating for coastal communities. Apollo Beach experienced significant storm surge flooding - water levels in some canal neighborhoods rose several feet above normal. Homes along the canal grid, especially older concrete block homes on lower lots, took on substantial water. The surge pushed bay water through the canal system and into streets, yards, garages, and ground-floor living spaces. Many of the original Apollo Beach waterfront neighborhoods - the homes along Bal Harbour Drive, Surfside Boulevard, and Golf and Sea Boulevard - were among the hardest hit.
Hurricane Milton (October 9, 2024)
Milton crossed the Florida peninsula and brought a different damage profile. While the storm surge was less severe than Helene's in some areas, Milton delivered stronger sustained winds and spawned tornadoes. Wind damage to roofs, pool cages, lanais, fences, and exterior features was widespread across Apollo Beach. Homes that had already been compromised by Helene's flooding took additional wind and rain damage from Milton. For many homeowners, this second hit was the tipping point - damage that might have been manageable from one storm became overwhelming from two.
The Combined Impact
- Storm surge flooding - Canal-front and low-lying homes took on anywhere from inches to several feet of water. Saltwater intrusion damages drywall, insulation, electrical systems, cabinetry, and flooring.
- Wind damage - Roof shingles and tiles, pool cages, lanai screens, fences, soffits, and fascia took significant hits across the community.
- Mold growth - Any home that took on floodwater and wasn't dried out within 48--72 hours likely developed mold. In Florida's humidity, mold colonization after flooding is almost inevitable without immediate intervention.
- Seawall and dock damage - Waterfront properties saw seawall erosion, dock destruction, and boat lift damage from storm surge and debris.
- Electrical and HVAC systems - Ground-level flooding damaged AC units, electrical panels, and wiring in many homes.
For a broader overview of Apollo Beach, including neighborhoods, pricing, and flood zone details, see my Apollo Beach Community Guide.
Assessing Your Damage - What to Look For
Before you can make any decision about selling, repairing, or staying, you need a clear-eyed assessment of what you're dealing with. Not all hurricane damage is equal, and the type of damage directly affects your options and your home's value.
Structural vs. Cosmetic Damage
- Cosmetic damage - Damaged drywall, stained flooring, ruined cabinets, peeling paint, broken pool cage panels, missing fence sections, damaged landscaping. This is expensive and disruptive, but it doesn't compromise the safety or integrity of the home.
- Structural damage - Foundation issues from soil erosion, compromised roof trusses, damaged load-bearing walls, cracked or shifted block walls, significant seawall failure. Structural damage is a different category entirely - it affects the fundamental integrity of the home and requires engineering assessment.
Mold Risk After Flooding
This is the hidden cost that catches homeowners off guard. If your home took on floodwater and wasn't professionally dried within 48--72 hours, mold is almost certainly growing behind walls, under flooring, and in any space where moisture was trapped. Mold can develop unseen for weeks or months before becoming visible. If you haven't had a mold assessment, get one now - the longer you wait, the more expensive the remediation becomes. For a detailed breakdown, read my Florida Mold Guide for Homeowners.
Insurance Claim Status
- Claim filed and settled - You know what your insurance will pay and can plan accordingly.
- Claim filed but still open - Your adjuster hasn't finalized the payout, or you're disputing the settlement amount. This is the most complex situation for sellers.
- No claim filed - If you have damage and haven't filed, do it now. Florida has specific deadlines for hurricane-related claims, and waiting too long can jeopardize your coverage.
- No flood insurance - If your home flooded and you didn't carry flood insurance, you're facing the full cost of repairs out of pocket. This changes the math on every decision.
Option 1: Repair and Sell at Full Market Value
If your insurance covers the majority of repairs and you have the time and financial capacity to complete them, this is almost always the best financial outcome. A fully repaired home sells for significantly more than a damaged one, and the Apollo Beach waterfront market will recover - it always does.
Timeline
- Repair period: 2--6 months depending on scope and contractor availability
- Listing to closing: 30--90 days in a normal market
- Total time from decision to sold: 3--9 months
Typical Repair Costs After Flooding (Apollo Beach)
| Repair Category | Estimated Cost Range |
|---|---|
| Drywall removal and replacement (per room) | $1,500--$4,000 |
| Flooring replacement (whole home, 1,500 sq ft) | $6,000--$15,000 |
| Kitchen cabinet replacement | $5,000--$20,000 |
| HVAC system replacement | $5,000--$12,000 |
| Electrical panel and rewiring (if flooded) | $3,000--$8,000 |
| Mold remediation | $2,000--$20,000+ |
| Roof repair (wind damage) | $3,000--$15,000 |
| Full roof replacement | $12,000--$30,000 |
| Pool cage replacement | $5,000--$15,000 |
| Seawall repair | $10,000--$50,000+ |
| Dock repair or replacement | $5,000--$25,000 |
| Exterior paint | $3,000--$7,000 |
ROI on Repairs
In my experience working with Apollo Beach sellers post-storm, a fully repaired home typically sells for 85--100% of its pre-storm market value, depending on the quality of repairs and documentation. A home sold as-is with significant damage typically goes for 50--70% of pre-storm value. The math usually favors repairing - especially if insurance covers a substantial portion of the cost. The key is making sure the repairs are done right, properly permitted, and fully documented.
Option 2: Sell As-Is to Cash Buyers or Investors
For some homeowners, repairing isn't feasible - whether because of finances, time, emotional exhaustion, or all three. Selling as-is to a cash buyer or investor is a legitimate option, and it has clear advantages in certain situations.
When Selling As-Is Makes Sense
- You don't have flood insurance and can't afford the repair costs out of pocket
- The insurance settlement is far below the actual repair cost and you can't bridge the gap
- You need to relocate quickly for work, family, or health reasons
- The emotional toll of managing a months-long renovation is more than you can handle right now
- The home had pre-existing issues that make a full renovation impractical
What to Expect
- Price - Cash investors typically offer 50--70% of the home's pre-storm market value, depending on the extent of damage. On a home that was worth $400,000 pre-storm, expect offers in the $200,000--$280,000 range for significant damage.
- Timeline - Cash sales can close in 2--4 weeks. No appraisal contingency, no lender delays, no repair negotiations.
- Condition - You sell the property exactly as it sits. No cleaning, no repairs, no staging.
- Costs - You still pay closing costs and agent commissions (unless you sell directly to an investor, which I'd recommend against without representation - more on that below).
A word of caution: the weeks after a hurricane bring a flood of "We Buy Houses" solicitations - mailers, door hangers, cold calls. Many of these are legitimate investors, but some are predatory operators who will lowball you significantly below fair market value because they know you're in a difficult spot. Having an agent who knows the Apollo Beach market ensures you're not leaving tens of thousands of dollars on the table.
Option 3: Repair and Stay
Not everyone who reads this guide wants to sell. If you love Apollo Beach - the waterfront lifestyle, the community, the bay access - and the damage is manageable, repairing and staying is a completely valid choice. Here's when it makes the most sense:
- Your insurance covers most or all of the repair costs
- You have a strong emotional connection to the property and community
- The repairs, once complete, will bring the home to equal or better condition
- You're willing to invest in mitigation improvements (elevation, flood barriers, impact windows) to reduce future risk
- Your financial situation allows you to absorb any gaps between insurance proceeds and actual repair costs
If you decide to stay, I'd strongly recommend investing in improvements that reduce your vulnerability to future storms. Elevating HVAC and electrical systems, installing impact windows, upgrading to a rated roof, and addressing drainage issues around the property can all reduce your risk and lower your insurance premiums going forward. My Hurricane Preparedness Guide covers these upgrades in detail.
Florida Disclosure Requirements After Hurricane Damage
This is non-negotiable, and I want to be direct about it. If you sell a home in Florida that has sustained hurricane damage, you are legally required to disclose what you know. Trying to hide damage or minimize the disclosure is not just unethical - it exposes you to serious legal liability after the sale.
What Florida Law Requires
- Known material defects - Under the Johnson v. Davis standard (Florida Statute 689.25), sellers must disclose known facts that materially affect the value of the property and are not readily observable. Hurricane damage falls squarely in this category.
- Flood history - If your home flooded during Helene, Milton, or any previous event, you must disclose it. This includes the extent of flooding, what areas were affected, and what remediation was performed.
- Insurance claims filed - Buyers and their insurers will discover claims through the CLUE (Comprehensive Loss Underwriting Exchange) report. Attempting to hide claims that will surface during the buyer's insurance application is counterproductive and creates liability.
- Mold history - If mold was discovered and remediated, disclose the findings, the remediation company, the scope of work, and the clearance testing results.
- Repairs completed - Disclose what repairs were made, whether they were permitted, and who performed the work. This actually works in your favor - documented, professional repairs reassure buyers.
My advice: Full disclosure is always the right strategy. Buyers in the post-storm Apollo Beach market expect some level of storm history. A seller who discloses thoroughly and provides documentation is far more likely to close a sale than one who tries to minimize or hide the damage. Transparency builds trust, and trust closes deals.
Insurance Claim Considerations When Selling
Your insurance situation adds a layer of complexity to selling after hurricane damage. Here's what you need to understand.
Selling With an Open Claim
If your insurance claim is still open when you list the property, the sale becomes more complicated. The buyer's lender may require the claim to be resolved before closing. You'll need to coordinate with your insurer about transferring or settling the claim. Some buyers will back out rather than deal with the uncertainty of an open claim. My recommendation: if possible, resolve your insurance claim before listing. If that's not feasible, work with an agent who has experience navigating this situation - it requires careful coordination between the seller, buyer, both agents, the title company, and the insurance carrier.
Assignment of Benefits (AOB)
If you signed an Assignment of Benefits with a contractor, you transferred your right to file and negotiate the insurance claim to that contractor. This can complicate a sale because the contractor now controls part of the insurance process. Be very careful with AOBs - and if you haven't signed one, I'd generally advise against it. Florida has tightened AOB regulations in recent years, but they still create complications in real estate transactions.
CLUE Report Impact
Every insurance claim you file goes on your property's CLUE report - a database that insurers use to evaluate risk. When the buyer applies for homeowners insurance, the insurer will pull the CLUE report and see the storm claims. Multiple claims can make insurance harder to obtain or significantly more expensive for the new buyer. This is a reality of post-storm selling, and it's another reason why having an experienced agent matters - we can help position the property correctly and connect buyers with insurers who work with storm-affected properties. For more on Florida homeowners insurance, see my detailed guide.
How Hurricane Damage Affects Home Value in Apollo Beach
Let me give you the honest picture. Hurricane damage does affect property values - but the impact isn't permanent, and the degree depends on several factors.
Short-Term Impact (0--12 Months Post-Storm)
- Damaged homes sell at significant discounts (30--50% below pre-storm value depending on severity)
- Repaired homes sell at modest discounts (5--15% below pre-storm value)
- Buyer pool shrinks because some buyers avoid storm-affected areas entirely
- Insurance costs rise across the community, which reduces what buyers can afford to pay
- Appraisals may come in lower due to recent distressed sales being used as comparables
Long-Term Recovery (1--5 Years)
- Historically, waterfront communities in Tampa Bay recover to pre-storm values within 2--4 years
- Homes that were repaired with upgrades (new roof, impact windows, elevated systems) often exceed pre-storm value
- The waterfront premium in Apollo Beach is fundamental - bay access and canal living drive demand that recovers
- Community-wide improvements (seawall repairs, drainage upgrades, infrastructure investment) support recovery
- New buyers are attracted by temporarily lower prices, which helps stabilize the market
The bottom line: Apollo Beach's waterfront location is its permanent value driver. Storm damage creates a temporary dip, not a permanent decline. But timing matters - selling in the immediate aftermath at a deep discount means leaving money on the table if you have the ability to repair and wait.
Working With Contractors After a Hurricane
Finding reliable contractors after a major storm is one of the biggest challenges homeowners face. Demand surges, supply is limited, and unfortunately, scammers follow the storms.
Finding Reputable Contractors
- Verify Florida contractor licenses at myfloridalicense.com
- Prioritize contractors who were operating in the Tampa Bay area before the storm - they'll be here after the job is done
- Ask for references from recent local jobs and check online reviews
- Get at least three written estimates before committing to any major work
- Confirm they carry workers' compensation and liability insurance
Red Flags - Avoiding Storm Chasers
- Door-to-door solicitation immediately after the storm
- Demanding large upfront deposits (more than 10--15% of the total job)
- No local address or out-of-state license plates
- Pressuring you to sign an Assignment of Benefits (AOB)
- Offering to waive your insurance deductible (this is insurance fraud)
- No written contract or vague scope of work
- Unwilling to pull proper permits with Hillsborough County
Permits Matter
All significant repair work - roofing, electrical, plumbing, structural - requires permits from Hillsborough County. Unpermitted work creates serious problems when you sell: it won't pass inspection, it may void your insurance coverage, and it will raise red flags for buyers and their lenders. Insist on proper permits for every job. Yes, it adds time. But it protects your investment and your ability to sell.