Quick Answer
Indian Rocks Beach is a built-out barrier island with limited inventory, strong demand from cash buyers and snowbirds, and median SFH prices of $700K-$900K. Non-waterfront homes move in 20-35 days. Gulf-front and canal properties take longer but sell at a premium. Insurance costs are the defining factor in affordability. Contact Barrett Henry at (813) 733-7907.
Indian Rocks Beach FL Real Estate Guide: Buyers and Sellers 2026
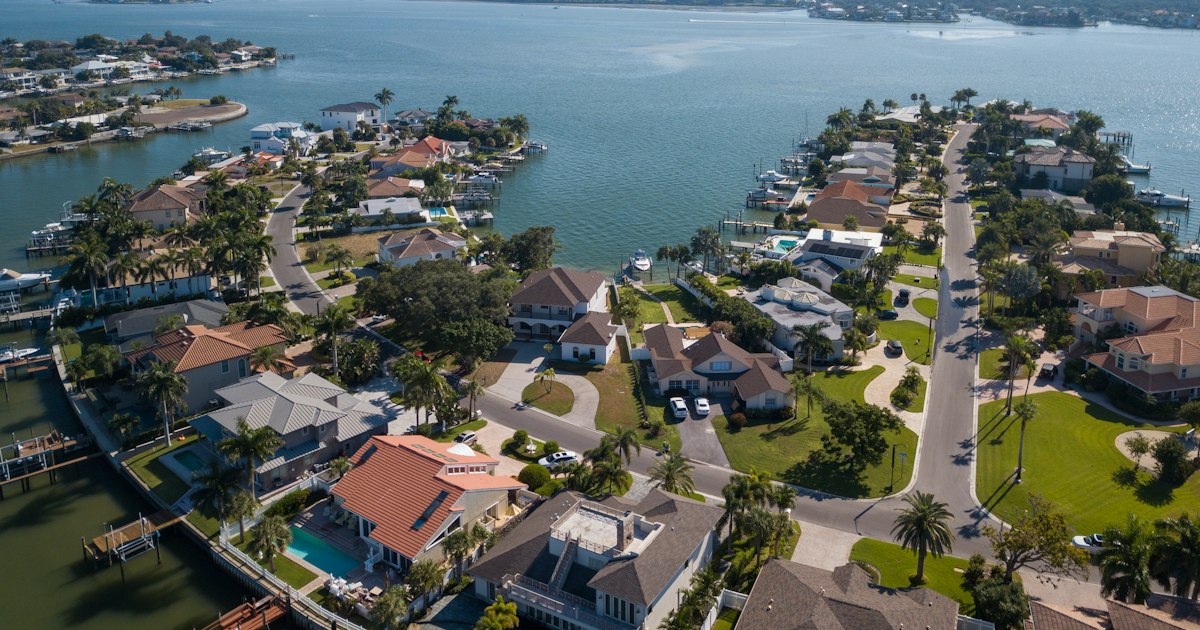
Indian Rocks Beach (ZIP 33785) is a 2.5-mile-long barrier island community in Pinellas County on Florida's Gulf Coast. The real estate market here is defined by structural supply constraints (built-out island, no new developable land), sustained demand from cash buyers and seasonal residents, and increasingly important insurance cost dynamics. This guide covers what both buyers and sellers need to understand to navigate this market successfully.
For active listings, check current Indian Rocks Beach homes for sale and the live housing market data. To plan your budget, the cost of living guide and mortgage calculator are your foundation.
What Are the Current Market Metrics for Indian Rocks Beach Real Estate?
| Metric | Current Range | Notes |
|---|---|---|
| Median SFH Sale Price | $700K-$900K | Varies significantly by waterfront status |
| Median Condo Sale Price | $380K-$600K | Building age, rental rules, and Gulf views matter |
| Price Per Sq Ft (SFH) | $350-$550/sqft | Higher for waterfront, lower for mid-island |
| Days on Market (Median) | 20-40 days | Well-priced non-waterfront moves faster |
| Sale-to-List Ratio | 96-99% | Sellers getting near ask on well-priced listings |
| Cash Buyer Share | ~35-45% | Higher than Tampa Bay average; snowbirds and investors |
| Concession Rate | 15-25% | Sellers offering closing cost help or credits in some price ranges |
| Active Listing Count | Low (30-60 at any time) | Inventory remains constrained on the island |
What Property Types Are Available in Indian Rocks Beach?
Non-Waterfront Single-Family Homes ($550K-$1.2M)
The core of the IRB market is non-waterfront SFHs on mid-island streets, 1-5 blocks from the beach. Most are 1,200-2,200 sq ft, 2-4 bedrooms, built between the 1960s and 1990s. Many have been renovated or updated. These properties appeal to primary residence buyers, snowbirds, and investors seeking vacation rental income. Even non-waterfront properties in IRB often fall in AE flood zones and require flood insurance, which is a key cost to factor into your analysis.
Canal-Front and Intracoastal Properties ($1.2M-$3M+)
The east side of IRB borders the Intracoastal Waterway and numerous finger canals. Properties here offer private docks, boat lifts, and direct ICW access. They are priced at a significant premium over non-waterfront. Buyers in this category are typically boat owners or investors targeting premium vacation rental income. Insurance costs are higher in this segment due to VE or high AE zone designations.
Gulf-Front / Beachfront Properties ($2M-$7M+)
Direct Gulf-front properties in IRB are the rarest and most expensive. These include detached single-family homes on Gulf Boulevard with direct beach access and Gulf-front condos and townhomes. Supply is extremely limited. Buyers in this segment are typically cash buyers, high-net-worth second-home purchasers, or investors with a long-term hold strategy. Insurance costs in VE zones can run $15,000-$40,000+/year and must be factored into the investment analysis.
Condos ($350K-$900K+)
Condo buildings in IRB range from older walk-up units from the 1970s to updated mid-rise buildings with Gulf views and amenities. Key considerations for condo buyers: warrantability for Fannie Mae/Freddie Mac financing (many vacation-rental-heavy buildings have financing restrictions), HOA rental policies (minimum rental periods affect STR income), special assessment history (deferred maintenance is common in older buildings), and reserve funding adequacy per the 2024 Florida condo inspection and reserve funding law changes.
Ready to Buy or Sell in Indian Rocks Beach?
Barrett Henry, 23+ years of real estate experience. REMAX Collective.
Contact BarrettCall (813) 733-7907What Strategies Should IRB Buyers Use in This Market?
Pre-Approval With Coastal-Experienced Lenders
Barrier island financing has nuances. Condo buildings need to pass agency review. High-value Gulf-front properties often require jumbo loans. Some properties have been previously damaged by storms and have prior insurance claims on file. Work with a lender experienced in Pinellas County coastal properties. Since August 2024, buyers must sign a buyer representation agreement with their REALTOR before touring properties under NAR settlement rules.
Get Insurance Quotes Before Going Under Contract
In IRB, this is not optional. Insurance costs on a barrier island can swing a property from affordable to unaffordable. Request an elevation certificate from the seller. Get flood, wind, and HO quotes before you make an offer. A property with a recent 4-point inspection and wind mitigation report makes insuring it significantly easier and cheaper. Budget conservatively: $8,000-$20,000/year total insurance on a typical IRB SFH is not unusual.
Due Diligence on Condo Buildings
If purchasing a condo, request and review: the condo association financials and reserve study, any pending or recent special assessments, the rental policy (minimum rental days, owner occupancy requirements), building inspection reports (required for buildings 3+ stories over 30 years old under the 2022 Florida Milestone Inspection law), and the HOA's insurance policy details. The 2022-2024 Florida condo reform laws created significant new requirements for older buildings.
What Strategies Should IRB Sellers Use?
Price Based on Current Insurance-Adjusted Comparable Sales
The market has adjusted to reflect insurance realities. Buyers are underwriting the true cost of ownership, not just the purchase price. Properties that are priced as if insurance costs have not increased will sit. Price from recent comparables that reflect current buyer behavior. A property with a current elevation certificate, recent 4-point and wind mitigation reports, and documented insurance history will attract buyers faster and command a better price than one requiring buyers to start fresh with all that documentation.
Prepare Insurance Documentation Before Listing
Have the following ready before listing: current elevation certificate, wind mitigation report (less than 5 years old), 4-point inspection report (less than 3-4 years old), your current insurance declarations page with annual premium, and any CLUE (Comprehensive Loss Underwriting Exchange) history. Buyers' agents are increasingly requesting this upfront. Sellers who have it ready reduce time-to-close and minimize contingency risk.
Timing the Market Seasonally
IRB has more seasonal price variation than most Tampa Bay submarkets. The winter snowbird season (November-April) sees increased buyer activity as northern buyers visit to escape cold weather. Listing in January-March typically generates the most showing activity. Summer listings still sell but buyer pool is smaller. For IRB sellers not in a hurry, the winter window is generally the optimal listing time.